One application. 12 lenders.
Apply Now One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.
Yes, from lenders that assess income and deposits before they look at the score. Twelve lenders lend below a 560 credit score. What changes with bad credit is not whether a loan exists but which lenders will write it, what they check instead, and what it costs.
Bad credit is also far more ordinary than the word suggests. On Smarter Loans, from January 2026 to June 2026, 23.6% of personal loan applicants carried a poor score, below 560, and a further 22.1% carried no usable score at all. Fair scores, 560 to 659, were the largest group at 46.3%. Only 8% of applicants had a good or great score. The lenders were built for the other 92%.
A score summarises the past. These lenders are more interested in the next three months, and they read those from your bank account.
Income and its regularity. Deposits that land on a schedule, from employment, self-employment, a pension or a benefit. Minimum income runs from $1,000 to $2,000 a month from any regular source, and four of the twelve lenders accept $1,000 or $1,200. This is the line that decides most applications.
What is already leaving the account. Existing loan payments, an outstanding advance, returned payments. A lender reading your statements sees these before it sees your score.
The score, last. It sets the rate within a lender's range and the tier of product you are offered. Every lender will consider a score below 560; none of them will ignore the deposits.
That order is the whole difference between this page and a bank. A bank starts with the score and stops there. A lender starts with the account.
The assumption most people bring to this page is that bad-credit borrowers ask for the most and get charged the most. The first half is wrong.
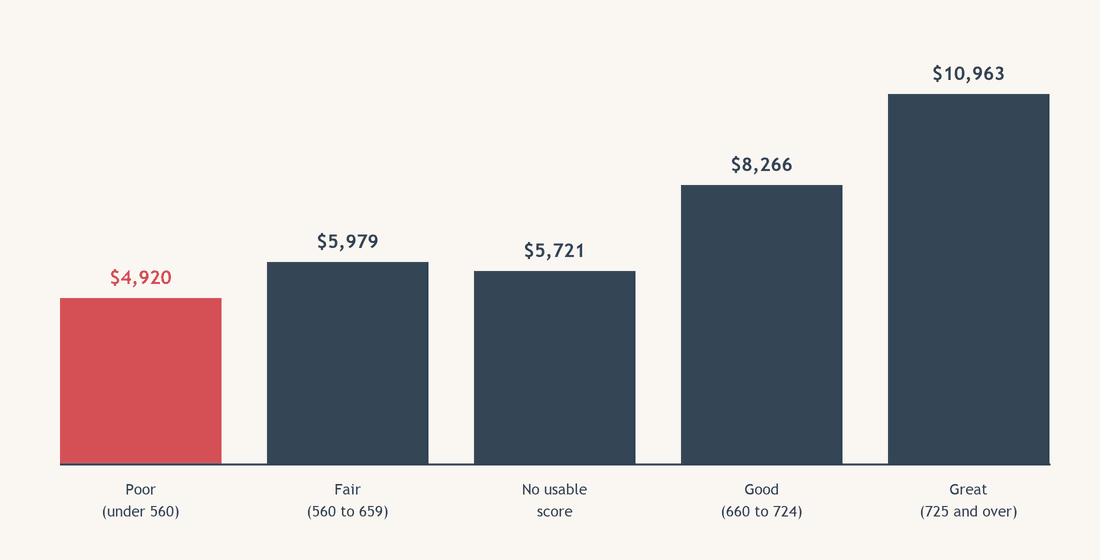
Use the figures below to check your request against what people in your band actually ask for. The band sets the rate more than the amount, so a request in line with these averages is the one that gets the better end of a lender's range.
| Credit band | Average personal request | Share of applicants |
|---|---|---|
| Poor (under 560) | $4,920 | 23.6% |
| Fair (560 to 659) | $5,979 | 46.3% |
| No usable score | $5,721 | 22.1% |
| Good (660 to 724) | $8,266 | 6.7% |
| Great (725 and over) | $10,963 | 1.3% |
Applicants with a poor score asked for $4,920 on average, the least of any band and less than half what applicants with a great score asked for. The pattern holds at the everyday scale too: below $1,500, poor-score applicants averaged $487 against $555 for good. People with damaged credit are, on our data, the most conservative borrowers on the platform.
What they borrow for follows the same shape as everyone else: paying off bills was the stated purpose on 33.0% of personal applications and debt consolidation on 20.4%, with consolidation requests averaging $8,155. Consolidation is the one purpose where a lower rate changes the arithmetic the most, and it is the one where a bad-credit borrower should run the numbers hardest before signing. Our debt payoff calculator does that comparison.
Approval is the easy part. The band decides the price.
Take $3,000 over 24 months. At 29.99% APR, roughly where a poor-score file lands with several of these lenders, the payment is about $168 a month and the interest about $1,025. At 19.99%, where a fair file might land, it is about $153 a month and $664 in interest. Same loan, same term, $361 of difference on the band alone.
That gap is why the cheapest thing a bad-credit borrower can do is often to borrow less, or later. Every lender is subject to the 35% federal cap on instalment loans, so the ceiling is fixed; the floor is where your file puts you. The personal loan calculator runs any amount, rate and term, and the number to watch is the total interest, not the monthly payment.
Rates run from 0% on the smallest fee-priced advances to the cap. Amounts run from $15 on those advances to $35,000 unsecured.
Both are searched constantly and neither describes a real product.
No credit check does not exist as an offer from a regulated lender. What exists is a soft inquiry that does not affect your score, with the decision resting on bank data, and several of these lenders work that way. A lender advertising no check at all is describing a soft pull, or is not a lender you want.
Instant approval describes the speed of a decision, not its likelihood. Some lenders decide within minutes on bank data; the decision can still be no.
Guaranteed approval is not a thing any regulated lender in Canada offers. Where you see it, the fees are usually due before the money is.
A loan repaid on time from a lender that reports to the credit bureaus is one of the few ways to move a score below 560 upward while doing something you needed to do anyway. Not every lender reports; the credit building loans page covers the ones whose products exist for that purpose.
A score moves slowly on the way up and quickly on the way down, which is why a single missed payment on a loan taken to rebuild undoes months of the rebuilding. If a payment will be tight in any month, a shorter term with a lower balance is safer than a longer one that looks affordable on paper.
Two things help more than most people expect. Check your own report first, free, through the Financial Consumer Agency of Canada's guidance; errors on reports are common and each one costs points. And apply once rather than to several lenders in a week, since a burst of hard inquiries lowers the score you are trying to protect. Our guide to going from bad credit to over 700 covers the longer route.
All personal loan options are on the personal loans hub. If the income on your file is a benefit rather than employment, the disability loans page and child tax benefit loans page cover how that is assessed. The figures describe what applicants with a poor score ask for; we do not publish how often they are approved.
Source for all platform figures: Smarter Loans personal loan applications, January 2026 to June 2026.
Reviewed by Vlad Sherbatov, Co-Founder and President, Smarter Loans. Last reviewed 6 September 2026. Platform figures cover applications from 1 January to 30 June 2026.
How to Get a Personal Loan in Canada with Bad Credit
Getting approved for a personal loan with bad credit: what lenders check instead of your score, what fair-credit borrowers request, and the traps to…
Credit Bands Across Canada: Who Applies With What Credit
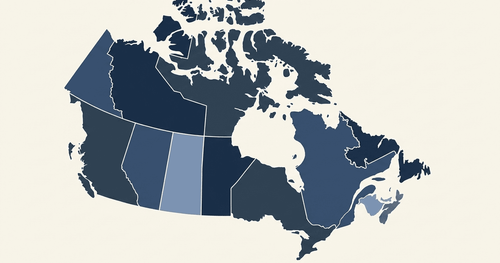
Fair credit is the largest self-reported band in almost every province, across more than 40,000 Smarter Loans personal loan applications in the year to July 2026. Saskatchewan is the only exception, where low credit leads, and good or great stays under one in seven everywhere.
Best Bad Credit Loans Instant Approval Canada
Bad credit loans in Canada: which lenders approve on income rather than score, what rates to expect, and what instant approval actually means.
Which Banks Are Easiest to Get a Loan From in Canada?
What makes a bank approve a loan, which types of institution are most flexible, and what to do when the bank says no.
Yes. Twelve lenders lend below a 560 credit score, assessing income and bank deposits before the score. On our platform in the first half of 2026, 23.6% of personal loan applicants had a poor score and 22.1% had no usable score; only 8% were good or great. Minimum income runs from $1,000 to $2,000 a month from any regular source.
None in particular; every lender listed considers scores below 560. The score sets the rate within a lender's range rather than deciding the application. Fair scores, 560 to 659, were the largest group on our platform at 46.3% of applicants, and these lenders are built for that applicant.
Lenders offer from $15 on the smallest advances to $35,000 unsecured. In practice applicants with a poor score asked for $4,920 on average in the first half of 2026, the least of any credit band. The amount that fits is the one whose total interest you have checked, not the maximum on offer.
Every lender is subject to the 35% federal cap on instalment loans, and the smallest fee-priced advances start at 0%. Where a poor-score file lands within that range depends on the lender and on your deposits. On $3,000 over 24 months, the difference between 29.99% and 19.99% is about $361 in total interest.
Not with no check at all. Several lenders use a soft inquiry that does not affect your score and decide on bank data instead. Any lender advertising no check whatsoever, or guaranteed approval, should be read carefully; those phrases usually sit beside fees due before any money arrives.