One application. 16 lenders.
Apply Now One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.
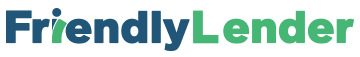
It depends on which lender says yes, and the spread is wide. Only ten of the sixteen lend that much. Two of those, easyfinancial and Spring Financial, start at 9.99%. The other eight all top out between 34% and the 35% federal cap. On $6,000, the average request here, that is the difference between paying about $970 in interest and paying about $3,770.
| Lender | Published rate | Monthly payment | Total interest over 36 months |
|---|---|---|---|
| Spring Financial | from 9.99% | $194 | $970 |
| easyfinancial | from 9.99% | $194 | $970 |
| Fora | from 19.9% | $223 | $2,020 |
| Cash 4 You | 34.37% | $269 | $3,690 |
| Cash Money | 34.99% | $271 | $3,770 |
$6,000 over 36 months at each lender's lowest published rate, monthly compounding. A lender's lowest rate is a starting point, not a promise: the rate you are offered depends on your application with that lender. Lender terms checked August 2026.
Treat the 9.99% as the best case rather than the likely one. Across all sixteen lenders the middle published rate is about 21%, so if your credit is average, the Fora row is a fairer guess than the top one. Whatever you are quoted, ask for the total in dollars over the term. Two lenders quoting 34.37% and 34.99% will cost you almost the same. Either of them against 9.99% is thousands.
Sixteen lenders, and you can rule out a few straight away. Four only do small advances. Bree and Nyble lend up to $750 and $250 at 0%. Eastern Loans and Friendly Lender stop at $750 and $1,000. Two more, Alterfina and Loan Away, stop at $2,500 and $5,000. If you need $6,000, your real choice is among the ten that go that high. Only two go above $20,000: Spring Financial to $35,000 and Money Mart to $25,000.
| Lender | Published rate | Amount | Pays out within |
|---|---|---|---|
| Bree | 0% | $15 to $750 | the hour |
| Nyble | 0% | $30 to $250 | 48 hours |
| easyfinancial | 9.99% to 34.99% | $500 to $20,000 | 48 hours |
| Spring Financial | from 9.99% | $500 to $35,000 | 48 hours |
| Alterfina | 18.99% | $500 to $2,500 | 24 hours |
| MDG Financial | 19.8% to 34.99% | $3,200 to $20,000 | 3 hours |
| Fora | 19.9% to 34.9% | $1,000 to $15,000 | 24 hours |
| Loan Away | 19.9% to 34.5% | $1,000 to $5,000 | 24 hours |
| Eastern Loans | 23% | $500 to $750 | 24 hours |
| Friendly Lender | 29.99% to 35% | $500 to $1,000 | 24 hours |
| Mogo | 34.37% | $500 to $15,000 | 48 hours |
| Cash 4 You | 34.37% | $100 to $20,000 | 24 hours |
| Money Mart | 34.56% to 34.95% | $500 to $25,000 | 48 hours |
| Magical Credit | 34.86% | $1,500 to $20,000 | 48 hours |
| Cash Money | 34.99% | $500 to $10,000 | the hour |
| LendDirect | 34.99% | $100 to $15,000 | the hour |
Published lender terms, checked August 2026. Rates are APR. Ordered by lowest published rate.
If speed matters more than price, the order changes. Cash Money, LendDirect and Bree pay out within the hour, MDG Financial within three, and ten of the sixteen within a day. The two cheapest lenders are not the quick ones: easyfinancial and Spring Financial both say 48 hours. You apply once. Our application goes to the lender most likely to approve the amount and purpose you give, and the others stay in reserve.
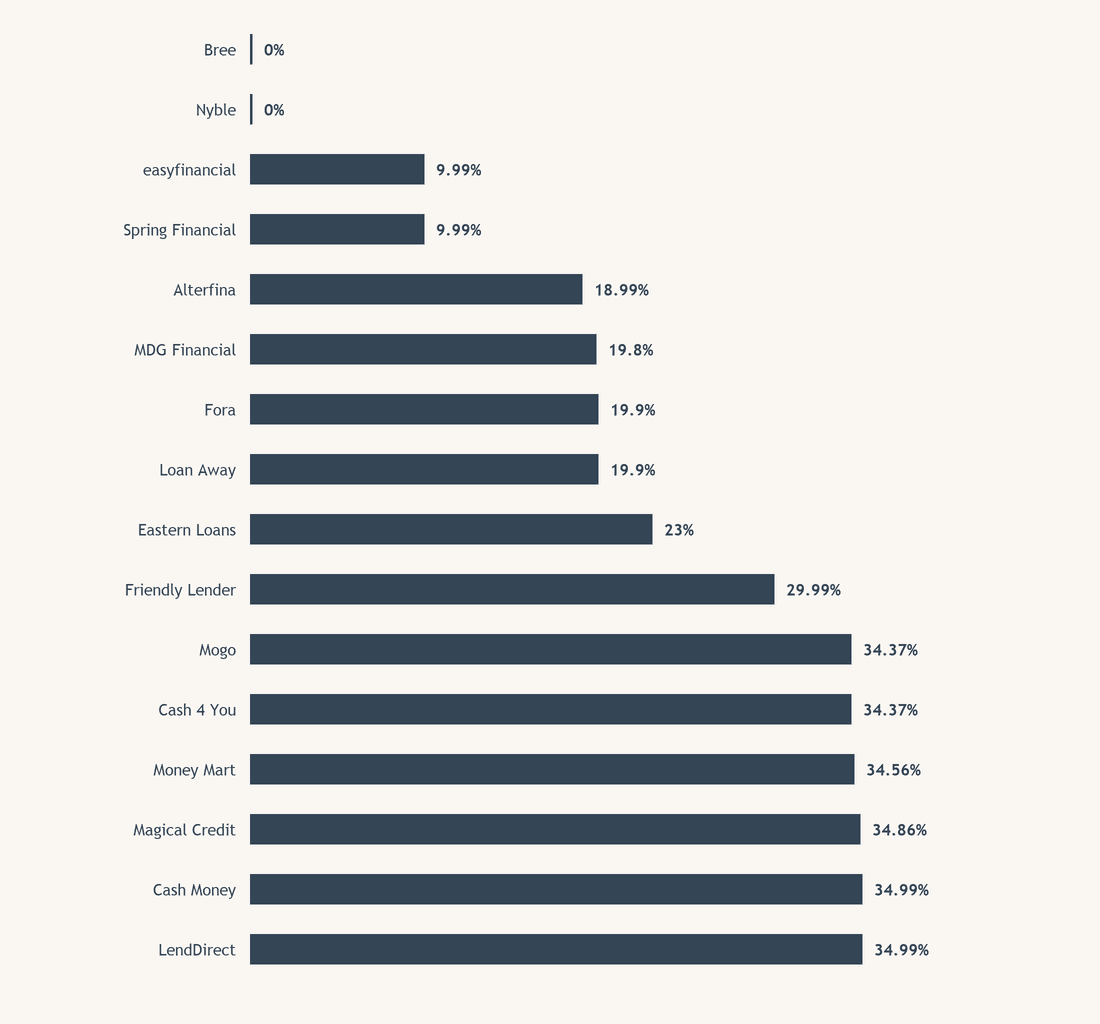
The average request from Toronto is about $6,000, which is no different from the rest of Ontario. What changes the number is the reason. If you are rolling a few debts into one loan, you will probably want closer to $7,700. If you are catching up on bills, closer to $4,900. Bills are the single most common reason, about three requests in ten.
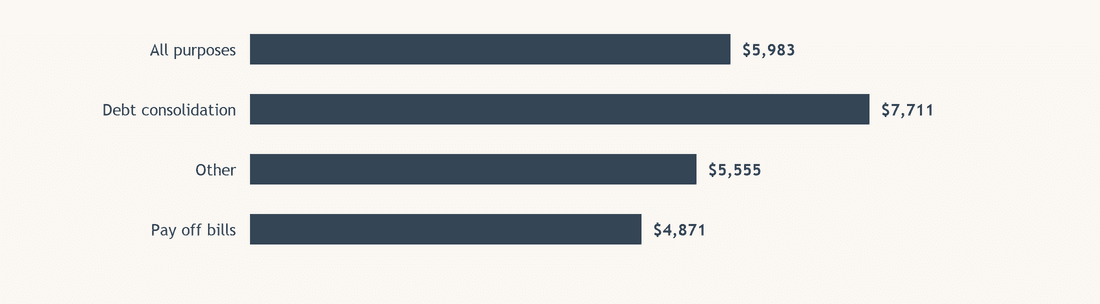
| Purpose | Average requested | Share of Toronto applications |
|---|---|---|
| All purposes | $5,983 | 100% |
| Debt consolidation | $7,711 | 19.9% |
| Other | $5,555 | 20.5% |
| Pay off bills | $4,871 | 30.2% |
Smarter Loans platform, 1,245 personal loan applications from Toronto, one in five of Ontario's, 1 January to 30 June 2026. Purposes with fewer than 100 applications are not shown.
If consolidation is your reason, the cost table above is the whole decision. A $7,700 loan at 34.99% only helps if the cards it pays off cost more than that. Check the rate on your card statement: if it is above the loan rate, consolidation saves you money, and if it is below, it does not. That is why easyfinancial and Spring Financial matter most to the people borrowing the most.
Slightly, and it changes who you should apply to. About a fifth of Toronto applicants have a score under 560, against nearly a quarter across Ontario. Nearly half are in the fair band, 560 to 659. About 8% are at 660 or better. Fewer people here live on benefits than in the province as a whole, about 8% against 11%.
| Applicants | Toronto | Ontario |
|---|---|---|
| Score under 560 | 19.2% | 22.9% |
| Score 560 to 659 | 47.1% | 44.5% |
| Score 660 or more | 8.4% | 7.8% |
| Full-time income | 66.5% | 65.9% |
| Benefits income | 8.3% | 11.0% |
Smarter Loans platform, personal loan applications, 1 January to 30 June 2026. Toronto n 1,245; Ontario n 6,222.
So if your score is in the 500s or low 600s, you are in the company of most Toronto applicants, and eleven of the sixteen lenders will consider you. Four have no minimum at all: Bree, Nyble, Alterfina and Eastern Loans, though none of the four lends more than $2,500. For $6,000 with a score under 560, the ones to look at are easyfinancial, Spring Financial, MDG Financial, Cash Money and Cash 4 You. All five list poor credit as acceptable. Income minimums run from $1,000 to $2,500 a month. Two of the sixteen accept disability or pension income. Magical Credit also counts child benefit and EI.
Then you are probably looking at a payday loan, and Ontario prices those differently. The cost is capped at $14 for every $100 you borrow, and you have two business days to cancel without penalty. On $500 that is $70, repaid in weeks. The lenders above charge an annual rate over months instead, so compare the two in dollars, not percentages. Lenders for the rest of the province are on the personal loans in Ontario page.
Reviewed by Vlad Sherbatov, Co-Founder and President, Smarter Loans, 14 October 2026. Lender terms checked August 2026. Platform figures cover applications from 1 January to 30 June 2026.
Bree and Nyble lend at 0%, but only up to $750 and $250. For a loan of a few thousand dollars, easyfinancial and Spring Financial are the lowest, both from 9.99%. The other eight lenders that go past $5,000 top out between 34% and 35%.
About $970 in interest over three years at the lowest published rate, or about $3,770 at the highest. The lender decides which, so ask for the dollar total before you sign.
Cash Money, LendDirect and Bree pay out within the hour, and MDG Financial within three. The two cheapest, easyfinancial and Spring Financial, take up to 48 hours.
Yes. Eleven of the sixteen lenders consider it, and four have no minimum. About a fifth of Toronto applicants in the first half of 2026 were under 560, fewer than across Ontario.
easyfinancial and Magical Credit both list pension income, easyfinancial lists disability income, and Magical Credit also counts child benefit and EI. The other fourteen want income from work.