One application. 7 lenders.
Apply Now One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.

Canadian mortgage lending runs in three tiers, and knowing which one you belong in saves weeks and, usually, money.
A lenders are the banks and the large credit unions. Lowest rates, strictest rules: provable income on tax slips, a clean credit file, and a stress test at a rate above the one you will pay. If you can qualify with a bank, you should, and nothing listed below competes on price.
B lenders are federally or provincially regulated lenders with more flexible rules on income and credit, at a higher rate and usually with a lender fee. Self-employed borrowers who cannot show income the way a bank wants it, newcomers with short Canadian history, and people with a bruised credit history after a bankruptcy or a consumer proposal are the B lenders' market. Most of the seven lenders listed operate in this tier or arrange lending in it.
Private lenders lend against the property rather than the borrower, for a year at a time, at the highest rates and fees of the three. A bridge to a defined exit, not a place to stay; our private mortgages page explains when it fits.
The application below asks how you earn, what your credit looks like and what the property is, and routes on the answer. If you are already with a bank and want a lower rate or cash out, mortgage refinancing is a different question with its own page.
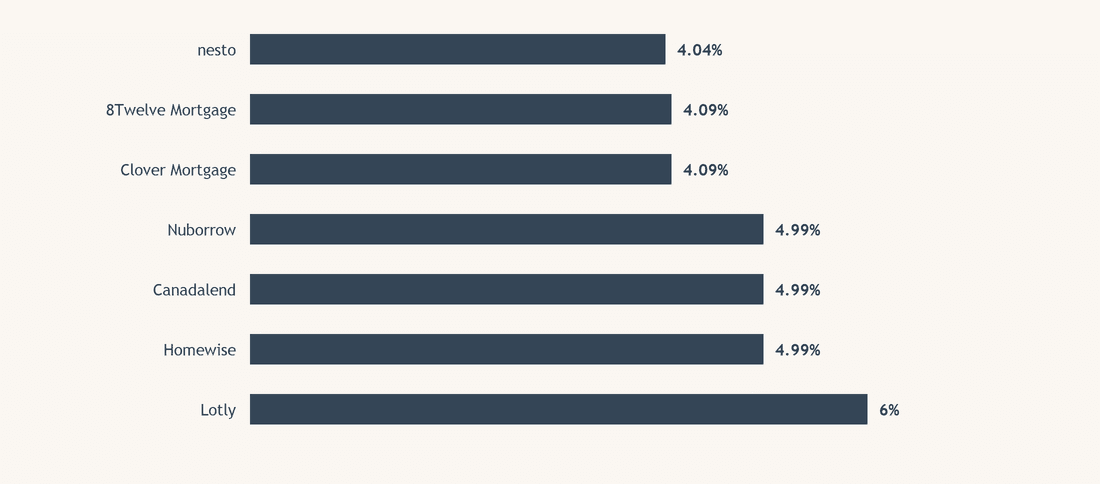
Rates with the lenders listed start between 4.04% and 6% and the highest published is 16%. The spread is the tier.
| Lender | Lowest published rate |
|---|---|
| nesto | 4.04% |
| 8Twelve Mortgage | 4.09% |
| Clover Mortgage | 4.09% |
| Nuborrow | 4.99% |
| Canadalend | 4.99% |
| Homewise | 4.99% |
| Lotly | 6% |
Use the table to see the floor each lender publishes, then read the rest of this section before assuming you will get it. A lender's lowest rate is its A-tier rate, offered to a borrower a bank would also take. The B-tier rate from the same lender sits one to three points higher and carries a fee, usually around one percent of the mortgage. A private rate sits higher again, in the teens, with a fee on top.
What that spread costs on a $400,000 mortgage over a 25-year amortisation: at 4.04% the payment is about $2,113 a month, at 6% about $2,559, and at 10% about $3,578. Across a five-year term that is roughly $126,766, $153,554 and $214,677 paid. The gap between the first and the second is the price of not qualifying at a bank; the gap to the third is the price of a private lender, and it is why private lending is for a year, not a life. The mortgage payment calculator runs any amount, rate and amortisation.
A federally regulated lender must also qualify you at a rate above the one you will pay, the stress test, which the Financial Consumer Agency of Canada explains in detail. B lenders regulated provincially and private lenders are not always bound by it, which is part of why they can say yes when a bank says no, and part of why they charge more.
Yes. Every one of the seven lenders listed considers poor credit, because the property is the security. What a bruised credit history changes is the tier, and with it the rate, the fee and the down payment.
A B lender will usually want a larger down payment than a bank, often 20% or more, and will price the risk rather than decline you. A discharged bankruptcy or a completed consumer proposal is not a bar; a recent one with no re-established credit moves you toward the private tier. The subprime mortgages page covers what B lenders look for after a bad stretch and how long it takes to move back to a bank, which is usually one term of clean payments.
If the problem is the income rather than the credit, self-employed income that shows on bank statements but not on tax slips, most of the lenders listed will read statements instead. That is the single most common reason a good borrower ends up at a B lender.
The property. Address, purchase price or appraised value, and what you already owe on it if you are refinancing. Federally regulated lenders lend up to 80% of the appraised value on a refinance; a standalone line of credit against a home is capped at 65%.
Income. Every lender listed sets a minimum of $1,500 a month, which tells you how little the number itself decides: what matters is how you prove it. Tax slips get the A-tier rate; bank statements get the B-tier rate; the property alone gets the private rate.
Down payment or equity. Five percent is the legal minimum on a purchase under $500,000 with mortgage insurance; twenty percent avoids insurance and is what most B lenders want. On a refinance, the equity you already hold is the down payment.
Credit. Considered by all seven, decisive with none. It sets the tier.
Time. Three lenders decide within two days; four take about a week. A mortgage closes on the appraisal, the title search and the legal registration, not on the approval, so budget two to four weeks from application to funds however fast the yes comes.
A fixed rate holds for the term, usually five years, and the payment does not move. A variable rate follows the lender's prime rate; the payment either moves with it or stays fixed while the share going to interest moves. Fixed is the safer choice when rates are rising or when the payment has to fit a tight budget; variable has cost less over most five-year periods in Canadian history and carries a smaller penalty to break.
The penalty is the part people miss. Breaking a fixed mortgage before the term ends can cost the greater of three months' interest or an interest rate differential that runs to tens of thousands on a large balance; breaking a variable usually costs three months' interest. If there is any chance you will sell, refinance or move in the term, that difference matters more than a quarter point on the rate.
Nine pages sit under this one, each for a specific situation, and the lenders on each are the ones whose products fit it.
Reviewed by Vlad Sherbatov, Co-Founder and President, Smarter Loans. Last reviewed 16 September 2026. Lender figures are the lenders' published terms as checked August 2026.
Which Lender Is Best for Your Mortgage in Canada?
Which lender approves which file: salaried, self-employed, bruised credit, newcomers and high-value mortgages, and how to choose.
Mortgages vs Home Equity Loans in Canada: Which Is Right for You?
Canadian Homeowner Tax Deductions & Credits You Shouldn’t Miss
Which tax credits Canadian homeowners can claim, which renovations qualify, and exactly what records the CRA expects when you make the claim.
A mortgage from a lender with more flexible income and credit rules than a bank, at a higher rate and usually with a fee of around one percent. Self-employed borrowers who cannot show income on tax slips, newcomers and people with a bruised credit history are the B lenders' market. Most of the seven lenders listed operate in that tier or arrange lending in it.
Yes. Every lender listed considers poor credit, because the property is the security. Expect a larger down payment, often 20% or more, a higher rate and a lender fee. A discharged bankruptcy or a completed consumer proposal is not a bar; a recent one with no re-established credit moves you toward private lending, which is a year at a time.
On a $400,000 mortgage over 25 years, the payment is about $2,113 a month at 4.04%, about $2,559 at 6% and about $3,578 at 10%. The first is an A-tier rate, the second a typical B-tier rate, the third a private rate. The gap is the cost of how you qualify, not of the property.
Fixed if the payment has to fit a tight budget or rates are rising; variable has cost less over most five-year periods and is cheaper to break. The penalty matters more than the rate if you might sell or refinance inside the term: breaking a fixed mortgage can cost an interest rate differential that runs to tens of thousands, breaking a variable usually costs three months' interest.
Three of the seven lenders listed decide within two days and four take about a week, but a mortgage closes on the appraisal, the title search and the legal registration rather than on the approval. Budget two to four weeks from application to funds.

