One application. 7 lenders.
Apply Now One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.

The lender underwrites the property's income rather than your salary, which changes every number in the transaction.
| Down payment | 25% to 35%, against 5% to 20% on residential. |
| Term | One to five years, shorter than residential. |
| Amortization | 15 to 25 years. |
| Central test | Debt service coverage from the rent roll, not personal income. |
A mortgage on a property that earns money, or on a property owned by a business, rather than on the home you live in. Five kinds come up most.
Multi-unit residential. Apartment buildings of five units and up. The easiest commercial property to finance, because the income is predictable and the resale market deep; lenders will go highest on loan-to-value here.
Mixed use. A shop with apartments above, an office with a storefront. Priced between residential and pure commercial, depending on how much of the income is from the residential side.
Retail, office and industrial. Financed on the leases in place: who the tenants are, how long they are signed for, and what happens if the anchor leaves.
Owner-occupied. A business buying the building it operates from. Priced on the business's own financials rather than on rent, and often the best fit for the lenders listed.
Land and special-purpose buildings. Raw land, hotels, gas stations, places of worship. The hardest to finance, because a lender that has to sell has few buyers; expect low loan-to-value and high rates, or private lending.
On the property, not on you. The single number that decides most commercial applications is the debt service coverage ratio: the property's net operating income divided by the annual mortgage payments. Most lenders want at least 1.25, meaning the property earns 25% more than the debt costs, and a stronger property or a weaker market moves that up or down.
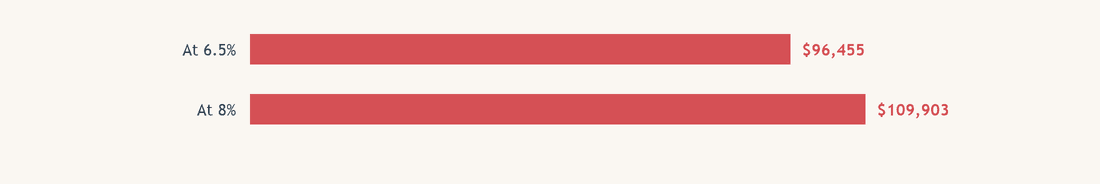
| Annual debt service on $1.2 million over 25 years | |
|---|---|
| At 6.5% | about $96,455 |
| At 8% | about $109,903 |
Use the figures to work backward from a property's income to what it can carry. A building with $120,000 of net operating income at a 1.25 coverage ratio supports about $96,000 a year in payments, which at 6.5% over 25 years is a loan of roughly $1.19 million. At 8% the same income supports about $1.05 million. The rate moves the loan size, not just the payment, and that is why commercial lenders quote a rate and a maximum loan together.
None of the seven lenders listed publishes a commercial rate, because commercial rates are set deal by deal on the property, the tenants, the borrower and the loan-to-value. What they publish are residential floors of 4.04% to 6%, and a commercial rate sits above the residential rate from the same lender for the same borrower. Loan-to-value runs lower than on a home, commonly 65% to 75% and lower still on special-purpose property, so the down payment is larger.
Two costs a residential borrower never sees. An environmental assessment, required on most commercial property and taking weeks. And a commitment or lender fee, usually a percentage of the loan, on top of the appraisal and legal costs.
Three of the seven: 8Twelve Mortgage, Clover Mortgage and Canadalend each publish a commercial mortgage service on their own site, arranging financing from multi-unit residential through retail and office with specialised commercial lenders. The other four lenders listed are residential lenders and are shown because they render on every mortgage page in the network; they will not take a commercial application.
The application below asks what the property is and what it earns, and routes to the three that arrange commercial lending. For an owner-occupied building where the purchase is really a business expansion, the mid-market financing page covers term lending at that size, and the business loans page covers everything else a business borrows for.
The same property can be financed at very different terms depending on how the application is built, and four things move the terms more than anything else.
Lease length and tenant quality. A building with five years left on leases to a national tenant is financed on the leases; one with month-to-month tenants is financed on the lender's guess about the market. Longer, stronger leases get more loan and a lower rate, and a lease review is where a commercial lender spends its time.
Vacancy. A lender underwrites the income the building earns today, less an allowance for vacancy whether or not you have any. A building at full occupancy with a waiting list still gets underwritten at 95% or less. Know what allowance the lender uses before you rely on a coverage ratio you computed at 100%.
Coverage above the minimum. A property at 1.25 gets financed; one at 1.40 gets financed at a better rate and a higher loan-to-value, because the lender has room if a tenant leaves. If the numbers are close, a larger down payment buys the coverage.
Track record. A borrower who has owned and operated income property before, or run the business buying its own building for years, is priced better than a first purchase. Lenders ask for the last property or the last five years, and a clean history is worth a real amount on the rate.
None of the four is your credit score, which is the most common surprise. Personal credit is checked, and a personal guarantee is standard, but a commercial lender is buying the property's income, and a strong building with a mediocre borrower is financed more readily than the reverse.
The property's income, documented. A rent roll and copies of the leases for an income property; two years of the business's financial statements for an owner-occupied one. The lender is underwriting the income, so this is the application.
An appraisal and an environmental report. The lender orders both, you pay for both, and the environmental report is the step that most often surprises a first-time commercial borrower on timing.
A down payment of 25% to 35%. Lower on multi-unit residential, higher on special-purpose property.
Your own financials. The property carries the loan, but the lender wants to know the borrower can cover a vacancy. Corporate financials, a net worth statement, and a personal guarantee on most deals.
Time. Six to twelve weeks from application to funding is normal, against two to four on a residential mortgage. The environmental report and the lease review are what take the time.
Reviewed by Rafael Rositsan, Co-Founder and CEO, Smarter Loans. Last reviewed 16 September 2026. Lender figures are the lenders' published terms as checked September 2026; the worked example is illustrative.
It is priced on the property's income rather than on yours. Lenders divide net operating income by the annual payments and usually want at least 1.25, lend a smaller share of the value, commonly 65% to 75%, require an environmental report, and charge a lender fee. It takes six to twelve weeks rather than two to four.
Set deal by deal, and none of the seven lenders listed publishes one. They sit above the residential floors of 4.04% to 6% shown on the cards, with the gap set by the property type, the tenants, the loan-to-value and the borrower. On $1.2 million over 25 years, the difference between 6.5% and 8% is about $13,400 a year.
What the income supports. A property earning $120,000 a year net, at a 1.25 coverage ratio, carries about $96,000 a year in payments, which is roughly a $1.19 million loan at 6.5% over 25 years. Loan-to-value caps that at 65% to 75% of the appraised value, whichever is lower.
Three of the seven listed: 8Twelve Mortgage, Clover Mortgage and Canadalend, each of which publishes a commercial mortgage service on its own site. The other four are residential lenders shown because they appear on every mortgage page in the network. One application routes to the three.
Six to twelve weeks from application to funding is normal. The appraisal, the environmental report and the lease review are what take the time, and the environmental report is the step that most often surprises a first-time commercial borrower.

