One application. 1 lender.
Apply Now One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.
Rates and terms for these lenders are being verified against our data standard. Each joins the comparison above as its figures clear. Until then we show no numbers rather than unverified ones.
One lender in the Smarter Loans network, Spring Powersports, and it is worth saying why one. Powersports lending is a specialist field: dealers arrange it through a few lenders, banks do it for strong files as a personal loan, and private sales, which is how most used machines change hands, are hard to finance anywhere. The lender listed finances motorcycles, ATVs, side-by-sides, snowmobiles, jet skis and trailers, new, used or private, in every province and territory.
What it publishes: $3,000 to $75,000, rates from 8.99% to 34.95% by credit, terms from one year to fifteen, income of at least $2,000 a month and a credit score of 550 or better, with payout within two days.
Because the machine loses value faster and sells in a smaller, seasonal market. A snowmobile in March and an ATV in a wet spring are hard to sell, and a lender's recovery position weakens faster than on a car that sells any month of the year. That is why the sensible term on a powersports loan is shorter than the longest one offered, however low the payment looks.
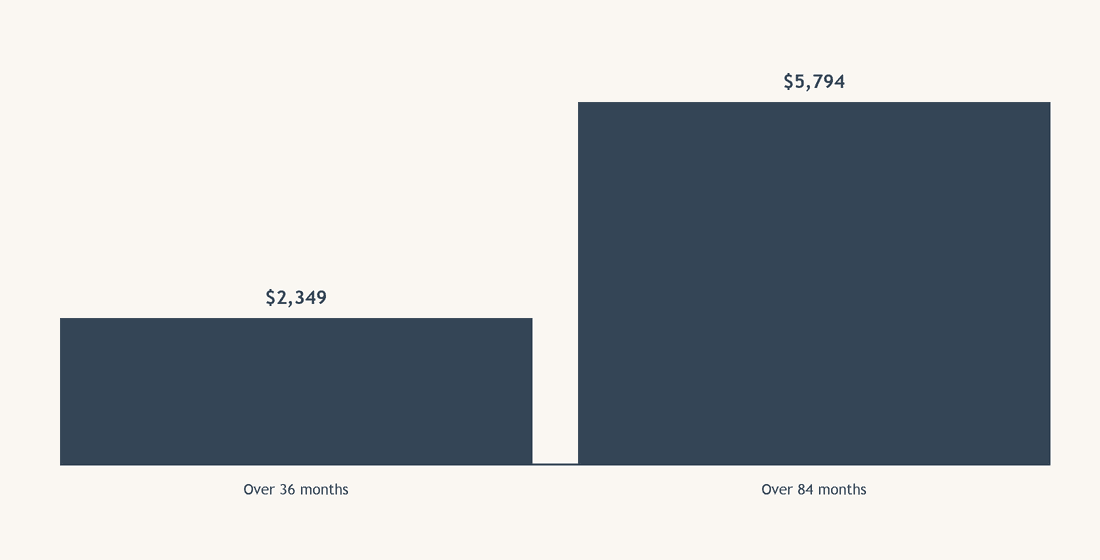
| $12,000 at 12% | Monthly payment | Total interest |
|---|---|---|
| Over 36 months | about $399 | about $2,349 |
| Over 84 months | about $212 | about $5,794 |
Use the table to price the term against the machine's life in your hands. Seven years on a $12,000 machine costs more than twice the interest of three years and outlasts the resale value by a wide margin; a payment that fits the season should fit a three-to-five-year term, and if it does not, the machine is too expensive for the budget rather than the term too short.
The same lender, the same range, and the term follows the machine.
Motorcycles. The largest resale market of the category and the longest sensible terms. New bikes from a dealer finance like a small car; used bikes are usually private sales.
ATVs and side-by-sides. Working machines as often as recreational ones, and a lender will ask which. Shorter terms, because hours and use wear them fast.
Snowmobiles. The most seasonal of all; a lender finances them year-round but the resale window is a few months. Keep the term short.
Jet skis and trailers. Financed on the same basis as boats; see the boat loans page for the survey and licensing steps on the water side.
Income of at least $2,000 a month from any regular source, and a credit score of 550 or better. The score sets the rate from 8.99% at the floor to 34.95% at the top.
The machine identified. Year, make, model, hours or kilometres, and the price or bill of sale. The lender finances a specific unit.
Registration and insurance where the province requires it. Rules differ by type and province: a motorcycle is a road vehicle everywhere, an ATV or snowmobile is registered for trail use in most provinces, and a lender will not fund a unit that cannot legally be used.
For a private sale, a lien search. A registered interest follows the machine, not the seller, and the lender listed pays the seller directly once the search is clean.
Most powersports machines are bought used and privately, and that is where the lender listed earns its place: it finances a private sale directly, which a bank rarely will and a dealer cannot. The trade-off is the work that falls to you. A dealer sale comes with an inspection, a warranty and paperwork the lender trusts; a private sale comes with a lien search, an inspection you arrange, and a price that is usually a third lower for the same machine. On a $12,000 dealer machine that is a $4,000 saving, which pays for a great deal of inspection.
New machines from a dealer finance at the bottom of the rate range and the longest terms, and for a machine you will keep for years the warranty is worth something real. Used machines from a dealer sit between. The lender scales the term to the machine's age and hours in every case, so a ten-year-old sled gets a short loan whatever the price.
Insurance, registration, trail permits, storage and maintenance, and on a snowmobile or ATV a season's fuel and trailering. A lender does not price any of it in. The buyer who works out a season's total cost and then sets the term to fit it is the buyer who still has the machine in three years.
The lender's own profile is at Spring Powersports; boats and other watercraft are on the boat loans page.
Reviewed by Vlad Sherbatov, Co-Founder and President, Smarter Loans. Last reviewed 16 September 2026. Lender figures are the lender's published terms as checked September 2026.
Yes. One lender in the Smarter Loans network finances motorcycles, ATVs, side-by-sides, snowmobiles and jet skis, new, used or from a private seller, from $3,000 to $75,000 at 8.99% to 34.95%, in every province and territory. You need $2,000 a month in income and a credit score of 550 or better.
The machine loses value faster and sells in a small, seasonal market, so the lender's security weakens quickly. Terms up to 180 months are offered, but three to five years matches the machine's life: $12,000 at 12% costs about $2,349 in interest over three years and about $5,794 over seven.
Yes. The lender listed finances private sales directly, with a lien search on the unit and payment direct to the seller. A registered interest follows the machine rather than the seller, which is why the search is a condition of funding.
550 or better with the lender listed, with the score setting the rate inside its range. A strong score gets the 8.99% floor; a weaker one sits toward 34.95%. All credit is considered.
Same lender, same range, shorter sensible term. A snowmobile's resale window is a few months a year, so a lender's recovery position is weaker and a long term outlasts the machine's value sooner. Keep it short.