One application. 4 lenders.
Apply Now One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.
Yes, and more readily than a personal loan for the same amount, because the car is the security. Four direct lenders in the Smarter Loans network are listed, and every one publishes an all-credit or no-credit-check program on its own site: one sets its floor at a 500 score, one publishes no minimum at all, and the other two consider poor credit as a matter of course.
On our platform in the first half of 2026, 23.6% of personal-loan applicants had a score under 560 and another 46.3% were in the fair band, which is to say seven in ten of the people who apply for a loan through us are somewhere below good. A poor score is not the exception for these lenders; it is the customer.
What changes with a poor score is not whether you are approved but what it costs, and that is the number to look at before the approval.
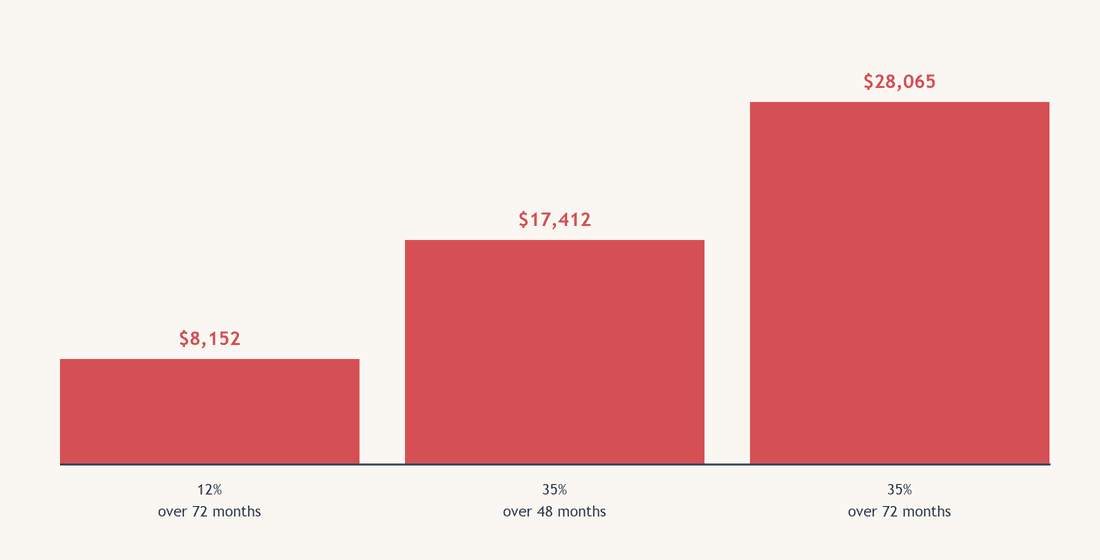
| $20,000 car loan | Monthly payment | Total interest |
|---|---|---|
| At 12% over 72 months | about $391 | about $8,152 |
| At 35% over 48 months | about $779 | about $17,412 |
| At 35% over 72 months | about $668 | about $28,065 |
Use the table before you sign anything. Rates with the lenders listed run from 6.93% to the 35% federal cap, and a poor score sits toward the top. At the cap over six years, a $20,000 car costs $28,000 in interest, more than the car; over four years it costs $17,400, still more than most people expect. The payment on the six-year loan looks affordable, which is exactly how a bad-credit buyer ends up paying for the car twice.
Two rules follow. Keep the term as short as the payment allows; the six-year loan at 35% costs $10,600 more than the four-year one. And do not accept a rate you can refinance out of in a year; twelve months of clean payments at 35% can be refinanced at a rate that reflects the new score, and the auto refinancing page covers how.
Three things, in order, and none of them is your credit.
The down payment. The single most effective lever. Ten percent reduces what the lender has at risk on a car that is losing value, moves the rate, shortens the term the lender will accept, and turns a decline into an approval more often than anything else you control.
The car. Newer, lower mileage, mainstream make and model. Lenders limit age and mileage because the security must hold value across the term, and a ten-year-old car is harder to finance than a three-year-old one whatever your score. A cheaper car is approved more readily than a payment shortfall is forgiven.
Your bank deposits. Direct lenders read three months of statements before they read the score. Regular income arriving on a predictable day, and an account without returned payments, is what a lender with an all-credit program is actually looking at.
A co-borrower with better credit helps where one is available, and a trade-in with positive equity works as a down payment.
Income of at least $1,500 to $2,500 a month depending on the lender, from any regular source, shown on bank statements.
The car identified: year, make, model, mileage, and the price or bill of sale. Lenders finance a specific vehicle and check its value against the loan.
A licence and insurance. A lender will not fund a car that cannot legally leave the lot.
A down payment, not always required, but the lever above.
A province the lender serves. Between them the four cover eleven provinces and territories; none serves the Northwest Territories or Nunavut, and one serves Quebec.
Every lender listed pays out within two days of approving you, and most decisions come back the same day.
Not before you have an approval of your own. Dealers arrange financing through lenders they work with and are paid a share of the rate, and at this credit band the rate and the price of the car get negotiated together, which is how a low payment hides a high price or a long term. In-house and buy-here-pay-here financing sits outside the mainstream market entirely, with the car's price marked up as well as the rate.
Get a direct lender's approval first through the application below, then let the dealer try to beat it. The approval separates the two negotiations, which at this band is worth real money. Our car loans in Canada page covers the dealer, bank and direct-lender routes in full.
If the credit is the larger concern than the car, the bad credit loans page covers what unsecured lenders look at; buying from a private seller is on the private sale car loans page.
Reviewed by Vlad Sherbatov, Co-Founder and President, Smarter Loans. Last reviewed 17 September 2026. Lender figures are the lenders' published terms as checked August 2026; the cost examples are illustrative. Platform figures cover applications from 1 January to 30 June 2026.
Yes. All four direct lenders listed publish an all-credit or no-credit-check program; one sets a 500 minimum score and one has no minimum. The car is the security, so approval is more available than for an unsecured loan at the same score. What changes is the rate, from 6.93% at the floor toward the 35% cap.
At the 35% cap, $20,000 over six years costs about $28,065 in interest, more than the car; over four years about $17,412. At 12% over six years, about $8,152. Keep the term as short as the payment allows and plan to refinance once a year of clean payments is on your record.
None is strictly required with several of the lenders listed, but ten percent is the single most effective thing you can do: it moves the rate, shortens the term the lender will accept, and turns declines into approvals more than anything else. A trade-in with positive equity works the same way.
Yes, with on-time payments. It adds an instalment account that reports to the bureaus, and twelve clean months at a high rate is usually enough to refinance at a rate that reflects the new score.
Not before you have an approval of your own. Dealer and buy-here-pay-here financing negotiates the rate and the car's price together, and the price is the part buyers miss. A direct lender's approval in hand separates the two.