One application. 2 lenders.
Apply Now One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.
Before anything else, because for most people it is.
A car title loan is secured on a car you own outright, and the security is what lets a lender say yes to someone with poor or no credit. It is also what makes the loan dangerous: miss enough payments and the lender takes the car. A personal loan puts no asset at risk, is capped at the same 35% federal rate, and on our platform the lenders offering one consider applicants with poor credit far more often than people assume: twelve of the seventeen personal lenders in the network consider a score under 560, and several make the decision on bank statements rather than the score.
So the order is: apply once, let the application reach both kinds of lender, and take a personal loan if one comes back. The bad credit loans page shows what those lenders look at. A title loan is the answer when an unsecured loan does not come back and you own a car worth more than what you need.
You own the car outright, with no lien on it. The lender registers a lien against it, lends you a share of its value, and you keep driving it while you repay. When the loan is cleared the lien is discharged.
Two lenders in the Smarter Loans network offer one, and they work differently.
In Ontario, the lender wants a vehicle eight years old or newer, paid off and registered to you or your company, and lends up to about half the vehicle's Black Book rough value, less for vehicles far from the Greater Toronto Area. Loans run from $1,000 to $25,000 at 19% to 25%, over six to thirty months, paid out within two days.
In Alberta, British Columbia, Saskatchewan and Manitoba, the lender publishes no credit check and no employment history requirement, approves on the initial call, and pays out in as little as an hour. Loans run from $3,000 to $50,000 at 9% up to the 35% cap, over terms up to three years, with renewals and early payout available. It publishes no vehicle age limit, so an older car may qualify where it would not in Ontario; ask before applying.
Neither lends in Quebec or Atlantic Canada, and there is no title lender in the network for those provinces.
Rates run from 9% at the floor to 35%, the federal cap. Where you land depends on the lender, the vehicle's value against the loan, and the term.
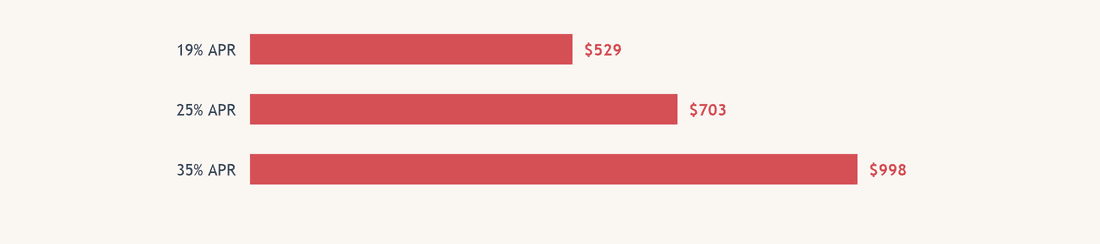
| Rate | Interest on $5,000 over 12 months |
|---|---|
| 19% | about $529 |
| 25% | about $703 |
| 35% | about $998 |
Use the figures to see what the rate range means in dollars before you decide on an amount. On $5,000 over a year, the difference between the Ontario lender's floor and the federal cap is roughly $470 in interest. A longer term lowers the payment and raises the total, and on a car that is losing value every month, a term that outlasts the car's worth is the trap to avoid.
Two things to establish before signing that the rate does not show. Whether there is a lien registration fee or an administration fee on top, since both lenders publish no fee schedule and you should ask for one in writing. And what early repayment costs; one lender publishes early payout as available, the other publishes nothing, so ask.
The car. That is the whole difference between this product and a personal loan, and it deserves to be said plainly.
The lender holds a registered lien. If you default, it can repossess the vehicle, sell it, and apply the proceeds to what you owe; in most provinces you remain liable for any shortfall after the sale. For most people who take a title loan the car is how they get to work, which means a missed run of payments can cost the income that would have repaid the loan.
Talk to the lender before the due date if a payment is at risk; the western lender publishes renewals, and a call before a default is worth more than any rate on the table. If the car needs repairs rather than money against it, the car repair loans page covers unsecured borrowing for the repair; if you still owe on the car, a title loan is not available and auto refinancing may be.
The 35% federal cap on interest applies to title loans as it does to every loan, and both lenders listed publish rates inside it. Provincial rules go further in some provinces than others.
Alberta, British Columbia, Manitoba and Quebec run high-cost credit licensing regimes, under which a lender charging above a threshold rate must hold a licence and meet disclosure rules; a title lender operating in those provinces should hold one, and the western lender listed names a high-cost credit licence on its own site. Ontario has no equivalent regime for title loans, so the Ontario lender is bound by the federal cap and general consumer protection law rather than a licence. The Financial Consumer Agency of Canada explains how title loans are regulated.
What that means for you: ask for the total cost of borrowing in dollars, the annual rate, every fee, and the repossession terms, in writing, before you sign. A licensed high-cost lender must give you that; an Ontario title lender should, and you should not proceed with one that will not.
A car you own outright, registered in your name, with no lien. In Ontario, eight years old or newer.
Income of at least $1,500 a month with both lenders, from any regular source. The western lender publishes no employment requirement.
Proof of the car's value. The lender will price against a published guide, and in Ontario against the rough value rather than the retail one; expect the loan to be about half of what the car would sell for.
Insurance and a licence, since you keep driving it.
Not your credit. One lender publishes no credit check; the other considers poor credit. This is the product that exists for people a personal lender has declined, which is exactly why the personal loan should be tried first.
If the aim is cash against an asset you own, the collateral loans page covers other assets, and every unsecured option is on the personal loans page.
Reviewed by Rafael Rositsan, Co-Founder and CEO, Smarter Loans. Last reviewed 16 September 2026. Lender figures are the lenders' published terms as checked August 2026; personal-loan comparisons are drawn from the lenders listed on our personal loans page.
You borrow against a car you own outright. The lender registers a lien on it, lends a share of its value, usually about half in Ontario, and you keep driving it while you repay. Two lenders in the Smarter Loans network offer one: in Ontario from $1,000 to $25,000 at 19% to 25%, and in Alberta, BC, Saskatchewan and Manitoba from $3,000 to $50,000 at 9% up to the 35% cap.
Only after a personal loan has been tried and declined, and only for an amount you can repay without risking the car. It puts your vehicle at risk for a rate that is rarely lower than an unsecured loan's. The same application reaches personal lenders, and twelve of the seventeen in the network consider a score under 560.
The lender can repossess and sell the car and apply the proceeds to what you owe; in most provinces you remain liable for any shortfall. Talk to the lender before the due date if a payment is at risk; a call before a default is the most valuable thing you can do.
Yes. The western lender publishes no credit check and no employment history requirement; the Ontario lender considers poor credit. The car's value and your income of at least $1,500 a month are what decide it. That is also why it costs what it does and why the car is at risk.
No. The two lenders listed serve Ontario, Alberta, British Columbia, Saskatchewan and Manitoba. There is no title lender in the network for Quebec, Atlantic Canada or the territories. The 35% federal cap applies everywhere, and Alberta, BC, Manitoba and Quebec also license high-cost lenders.