One application. 7 lenders.
Apply Now One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.

Seven in the Smarter Loans network, from $15,000 to $100 million, at 4.04% for an A-tier borrower up to 16% for private money. Every one considers poor credit, because the property is the security, and every one wants $1,500 a month in income. Two of the seven lend in every province and three arrange B and private lending for a borrower a bank has declined; three of the seven pay out within two days of approval, and the rest wait for an appraisal. One application reaches all seven and is placed with the tier your application fits.
A-tier is bank-level pricing for a borrower who proves income on tax slips and passes the stress test; the 4.04% floor belongs to that tier. B-tier is for self-employed income, a recent credit event or a high debt ratio, priced one to two points higher with a fee. Private is for a borrower neither will take, or a property neither will lend on, priced toward the top of the range and often interest-only for a year or two. The gap between tiers is real money: on $500,000 over 25 years, 4.04% costs about $2,641 a month and 6% about $3,199, a difference of about $47,000 in interest across the first five-year term. The subprime mortgages and private mortgages pages cover the two higher tiers in full.
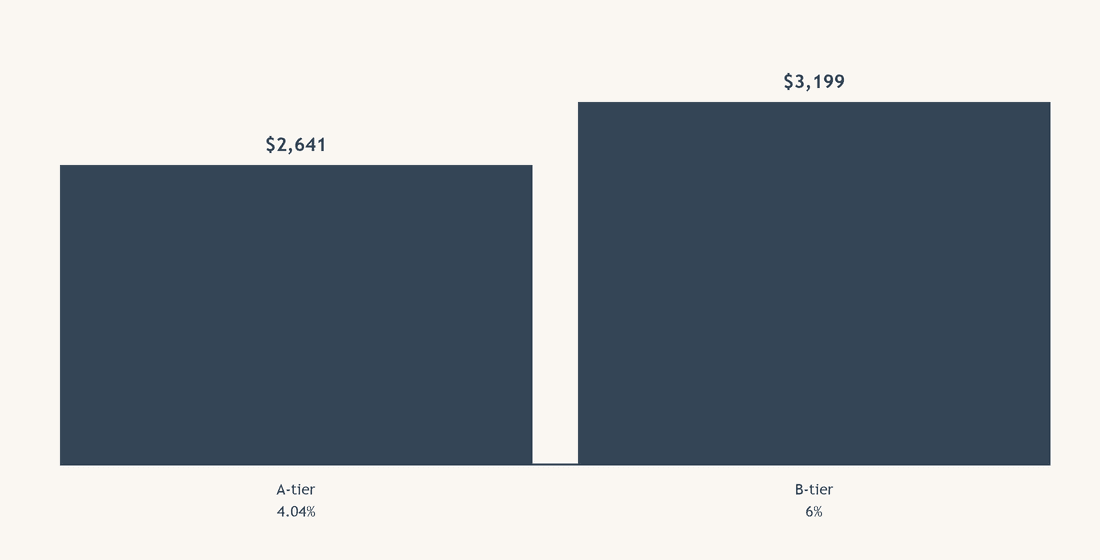
| $500,000 over 25 years | Monthly payment | Interest in the first five years |
|---|---|---|
| A-tier at 4.04% | About $2,641 | About $94,000 |
| B-tier at 6% | About $3,199 | About $141,000 |
Illustrative, Canadian semi-annual compounding; 4.04% is the lowest rate published among the lenders listed.
Land transfer tax, on every purchase: 0.5% of the first $55,000, 1% to $250,000, 1.5% to $400,000, 2% above that, and 2.5% on the part above $2 million of a home. On a $600,000 home that is $8,475, due on closing and not financeable inside the mortgage. A first-time buyer gets up to $4,000 of it back, which means no tax at all on the first $368,000. A purchase inside the City of Toronto pays a second, municipal land transfer tax on top, $8,475 on the same $600,000 home, with its own first-time rebate of up to $4,475. Add the lawyer, the appraisal and title insurance, and closing costs on a $600,000 Toronto purchase approach $20,000 before the down payment.
| Purchase price band | Ontario rate | On a $600,000 home |
|---|---|---|
| First $55,000 | 0.5% | $275 |
| $55,000 to $250,000 | 1% | $1,950 |
| $250,000 to $400,000 | 1.5% | $2,250 |
| $400,000 to $2,000,000 | 2% | $4,000 |
| Above $2,000,000, one or two family residence | 2.5% | — |
| Ontario land transfer tax | $8,475 | |
| First-time buyer refund | up to $4,000 | $4,475 net |
| Inside Toronto, municipal tax on top | $8,475, rebate up to $4,475 for a first-time buyer |
Five percent of the first $500,000 and ten percent of the rest, with mortgage insurance below 20% down; 20% down avoids the insurance premium and opens the conventional market, private lenders included. An insured mortgage carries the lower rate, an uninsured conventional one the wider choice of lender. On the $600,000 example, 5% of the first $500,000 and 10% of the rest is $35,000 down; 20% is $120,000.
Two years of income history, on tax slips for A-tier or bank statements for B; a credit report the lender pulls; the down payment with its source, because a gift and savings are treated differently; and the property, which the lender values. Every mortgage broker in the province must be licensed by FSRA, and a broker's licence number is on the FSRA register. For a loan against a home you already own, the home equity loans in Ontario page covers the lenders that lend into the equity without replacing the first mortgage.
Reviewed by Rafael Rositsan, Co-Founder and CEO, Smarter Loans. Last reviewed 23 September 2026. Lender figures are the lenders' published terms as checked August 2026; the payment examples are illustrative and use Canadian semi-annual compounding.
Seven in the Smarter Loans network arrange Ontario mortgages, from $15,000 to $100 million at 4.04% to 16%, across A, B and private lending. Every one considers poor credit because the property is the security.
Ontario charges 0.5% of the first $55,000, 1% to $250,000, 1.5% to $400,000, 2% above that and 2.5% above $2 million on a home. A $600,000 home carries $8,475, and a first-time buyer gets up to $4,000 of it back.
Yes. A purchase inside the City of Toronto pays a municipal land transfer tax in addition to the provincial one, $8,475 on a $600,000 home, with a first-time purchaser rebate of up to $4,475.
Yes. Every one of the seven lenders listed considers poor credit, and three arrange B and private lending for a borrower a bank has declined, at one to two points above A-tier pricing, or toward the top of the range for private money.
Federal rules require 5% of the first $500,000 and 10% of the rest, with mortgage insurance below 20% down. On a $600,000 home that is $35,000; 20% down, $120,000, avoids the insurance premium.