One application. 13 lenders.
Apply Now One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.
Eight of the lenders serving Toronto go as high as $6,000. Their rates run from 9.99% to just under the 35% legal cap. Over three years, that's the difference between about $970 in interest and about $3,770.
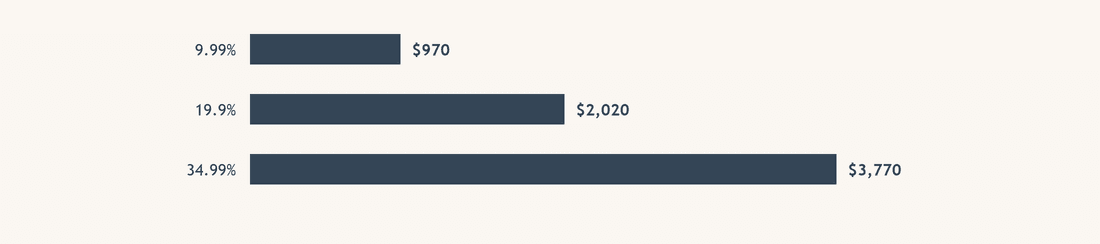
| Rate | Monthly payment | Total interest over 36 months |
|---|---|---|
| 9.99% | $194 | $970 |
| 19.9% | $223 | $2,020 |
| 34.99% | $271 | $3,770 |
$6,000 over 36 months, monthly compounding. Lender terms checked November 2026.
The 9.99% is the starting rate at easyfinancial and Spring Financial. A starting rate is a best case, not a promise. Across all thirteen lenders that serve the city, the middle starting rate is about 20%. So if your credit is average, plan around the 19.9% row. When an offer comes in, ask for the total in dollars. An offer at 34.37% and one at 34.99% cost you almost the same. Either one costs about $2,800 more than a loan at 9.99%.
The average request in Toronto is about $6,000, but your reason for borrowing moves that number. And the amount changes what's worth doing.
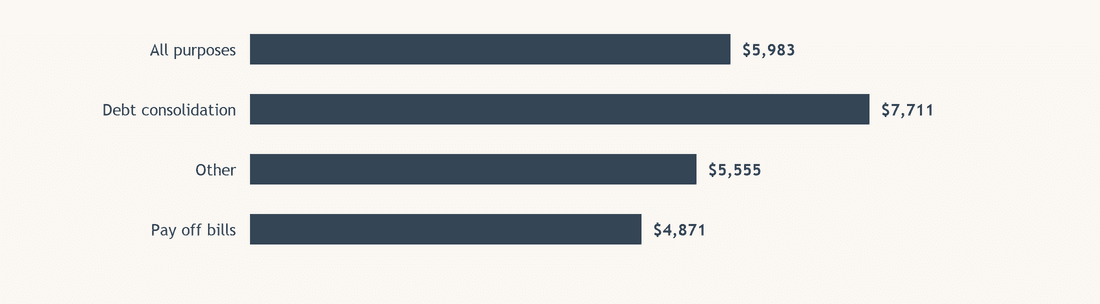
| Purpose | Average requested | Share of Toronto applications |
|---|---|---|
| All purposes | $5,983 | 100% |
| Debt consolidation | $7,711 | 19.9% |
| Other | $5,555 | 20.5% |
| Pay off bills | $4,871 | 30.2% |
Smarter Loans platform, 1,245 personal loan applications from Toronto, 1 January to 30 June 2026. Purposes with fewer than 100 applications are not shown.
Bills are behind three in ten Toronto applications, and the average request is about $4,900. Nine of the lenders will lend that much. If you can manage a bigger payment, take the shorter term. At 34.99%, repaying it over a year costs about $980 in interest. The payment is $490 a month. Over three years the payment drops to $222, but the interest climbs to about $3,080. The extra two years cost you $2,100.
About one in five Toronto applications is for consolidation, and those average about $7,700. Before you apply, check the rate on each card or loan you'd be paying off. Consolidation only saves money if the new loan's rate is lower. Over three years at 9.99%, that loan costs about $1,240 in interest. At 34.99% it costs about $4,840. One payment is easier to manage, but at the higher rate it can cost more than the debts it replaces.
Two in three people who apply from Toronto have a score under 660, so this is the usual case. About a fifth are under 560, against nearly a quarter across Ontario. Four of the eight lenders that go to $6,000 list poor credit as acceptable. Both lenders with the 9.99% starting rate are among them, so a low score doesn't rule out the cheapest loans. It does make them less likely. Four lenders have no minimum score, but none of them lends more than $2,500.
If your income is a pension or disability benefits, most lenders won't count it. easyfinancial counts both, and Magical Credit counts pensions, child benefit and EI.
MDG Financial is the quickest for $6,000, paying out within three hours. It lends from $3,200, with rates from 19.8%. Two more lenders pay within a day. The two lenders that start at 9.99% take up to 48 hours. If you'd qualify with them, waiting two days can save you about $2,800 over three years. For $750 or less, Bree pays within the hour at 0%. You apply once. Our application goes to the lender most likely to approve the amount and purpose you give, and the others stay in reserve.
Under $1,500 you're probably looking at a payday loan, and Ontario caps the cost at $14 for every $100 you borrow. You have two business days to cancel without penalty. On $500 that's $70, due back in weeks. Compare that with an installment loan in dollars, not percentages. Lenders for the rest of the province are on the personal loans in Ontario page.
Reviewed by Vlad Sherbatov, Co-Founder and President, Smarter Loans, 12 November 2026. Lender terms checked November 2026. Platform figures cover applications from 1 January to 30 June 2026.
easyfinancial and Spring Financial both start at 9.99%, and both lend $6,000. Starting rates go to the strongest applications, so many people are offered more.
At 9.99% over three years, it costs about $970 in interest. At 19.9% it costs about $2,020. At 34.99% it costs about $3,770. Ask for the dollar total before you sign.
Only if its rate is lower than the debts it pays off. Toronto consolidation requests averaged about $7,700 in the first half of 2026. Over three years, a 9.99% loan on that amount costs about $3,600 less than one near the cap.
Yes. Four of the eight lenders that lend $6,000 list poor credit as acceptable, including the two with the lowest starting rates.
MDG Financial pays out within three hours on loans from $3,200. easyfinancial and Spring Financial take up to 48 hours. For $750 or less, Bree pays within the hour at 0%.