One application. 7 lenders.
Apply Now One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.
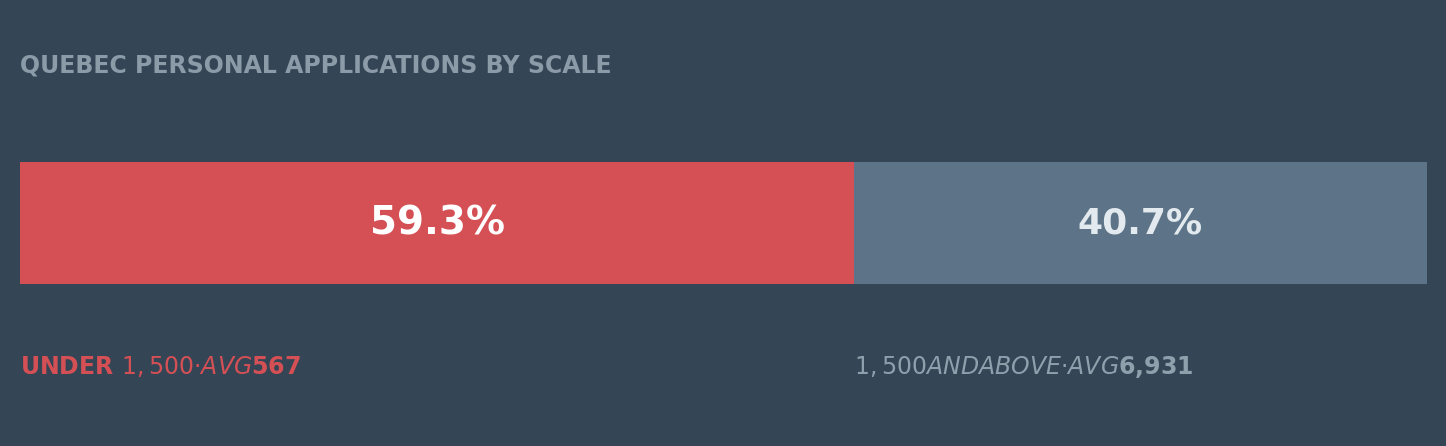
| Segment | Share | Average request |
|---|---|---|
| Everyday, under $1,500 | 59.3% | $567 |
| Instalment, $1,500 and above | 40.7% | $6,931 |
Payday lending does not operate in Quebec, and that is a saving rather than a restriction. $500 for two weeks costs about $70 in Ontario and about $7 in Quebec at the 35% cap. The 35% cap applies to every credit contract in the province, not only to small loans.
The rate is capped; membership and brokerage fees are not. The contract must state the total repayable, and that total is the only honest comparison between two offers.
The Office de la protection du consommateur does not issue permits above 35% annual interest. Where a rate exceeds the Bank of Canada rate plus 22 points, added obligations apply, including an ability-to-pay assessment.
Four gates, in the order lenders apply them.
The rest require employment or self-employment. This field decides more applications than credit score does.
Income floor is absolute. Most lenders publish a minimum monthly income, most commonly $1,500 per month. Below a lender's floor, nothing else compensates.
A decline is one lender's threshold, not the market's.
Banking history can replace credit history. Lenders that connect read-only to your account assess deposit regularity rather than your file, approve applications a bureau score would decline, and fund fastest.
Worth checking before borrowing. Each costs less than any loan.
When Should You Use a Personal Loan in Canada?
When a personal loan is the right tool and when it is not: what Canadians borrow for, what it costs against a credit card,…
What Canadians Borrow to Consolidate, by Province
Canadians applying to consolidate debt asked for an average of $6,659 in the year to July 2026, across more than 8,000 Smarter Loans applications. Newfoundland and Labrador led every province at $7,948 and New Brunswick sat lowest at $6,133.
Credit Bands Across Canada: Who Applies With What Credit
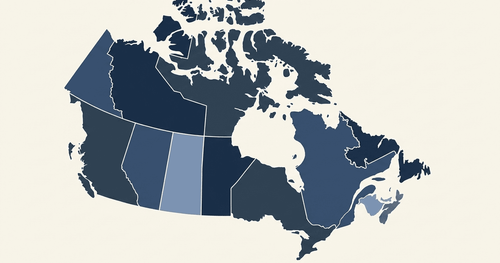
Fair credit is the largest self-reported band in almost every province, across more than 40,000 Smarter Loans personal loan applications in the year to July 2026. Saskatchewan is the only exception, where low credit leads, and good or great stays under one in seven everywhere.
How to Judge a Loan Company in Canada
What separates a reliable loan company from a risky one in Canada: licensing, real APRs, fees in writing, and what borrowers like you get…
To obtain a personal loan in Quebec, you need to follow a few simple steps: Decide what type of Quebec personal loan you need Find a personal loan lender in Quebec that you can work with Gather your paperwork Complete an application form
Not every personal loan lender in Quebec offers every type of loan, or will work with every applicant, so it’s important to shop around. Most private loans in Quebec will need proof of a steady income, and many perform a credit check. At an absolute minimum, you should be prepared to provide: I.D. Proof of address Income information Bank account information
If your personal loan application is approved, you will receive a loan offer from the lender that details the full terms of your loan. You need to carefully review these terms and accept them, before your loan funds will be released.
Personal loans in Quebec are widely available from a number of different types of personal loan lenders, such as: Banks Online lenders Credit unions Alternative lenders
The above all offer multiple different types of personal loan; but some personal loan lenders in Quebec specialize in just one type of personal loan. Among these are: Mortgage lenders Car loan companies and vehicle dealerships offering car loans Payday lenders Bad credit lenders Debt consolidation companies
Every type of personal loan lender in Quebec has their own advantages and disadvantages, as well as different eligibility criteria, so finding the right lender for you requires understanding your needs and situation.
Private personal loan lenders in Quebec offer every possible type of personal loan, from small loans, to large loans, to Quebec online loans. Each Quebec personal loan falls into one of two broad categories: secured, or unsecured.
Secured personal loans can sometimes be known as title loans, and these encompass any type of personal loan in Quebec that has an asset held against it as collateral. In the event of the borrower defaulting on their loan payments, the Quebec personal loan lender can seize the asset. Because secured personal loans have this form of guarantee, they are less risky for the lender, and so can be for larger amounts or longer terms than unsecured personal loans. Secured loans usually also have the best personal loan interest rates in Quebec. Examples of secured loans include car loans, mortgages, secured credit cards, and home equity lines of credit.
Unsecured personal loans in Quebec do not require assets as collateral; this makes them easier to qualify for, but more risky for the personal loan lender, and so they tend to be for smaller amounts, shorter terms, and have higher interest rates. Examples of unsecured personal loans include payday loans, lines of credit, credit cards, student loans, bad credit loans and debt consolidation loans.
All types of Quebec loans, including all of the secured and unsecured loans mentioned above, are widely available across the province, including as online personal loans - although the exact type, size, terms and rate for any given loan will depend on the borrower’s circumstances.
Personal loans in Quebec come in all sizes, from just a few hundred dollars, to as much as $50,000, or even more. The amount of money you are able to borrow depends on the type of loan you apply for, the lender you apply to, and your personal financial circumstances. The better your credit score and income, the more you’ll be able to borrow.
Personal loans in Quebec are available for a wide range of uses. Most common among the reasons for needing a personal loan are: Unexpected bills Monthly expenses Debt consolidation Home improvements Weddings Vacations Vehicle purchase or repair Emergencies
If you need cash for bills, emergencies, big purchases, or a combination of things, then there are many Quebec personal loans that may suit. Installment loans, lines of credit, payday loans, and bad credit loans all provide access to funds that can be used in any way you wish, with no restrictions.
However if you need help financing a vehicle purchase, startup costs for a business, debt consolidation, or something else very specific, then you might be better served by a personal loan tailored to that need. While the general-purpose personal loans mentioned above can all be used for these specific reasons, Quebec personal loans such as auto loans, student loans, business loans and debt consolidation loans may have better terms for those particular needs.
Whichever type of loan you choose, make sure you understand its terms and conditions before you apply. These typically relate to repayment schedules, fees, and so on, but may also include other conditions, so are always worth checking.
Quebec loan interest rates vary from person to person, from private loan lender to lender, and over time; they can depend on a number of factors, including the borrower’s income and credit score, the lender’s position in the market, as well as the loan type, and wider macroeconomic variables. For this reason it’s not possible to guarantee the best personal loan interest rate in Quebec that any given person will be able to get at any given time; what we can say is that the range of personal loan rates in Quebec right now is between 5% and 50%, with this very broad scope encompassing loans and borrowers of all types. The average unsecured personal installment loan interest rate is around 9%.
Private lenders for personal loans in Quebec take a number of borrower-specific factors into account when calculating personal loan interest rates for their applicants, with the goal of assessing how risky each borrower is to lend to, and therefore how much they should charge in interest. The riskier you are perceived to be, the higher the personal loan interest rate. These are the factors most often used: Income Steady income is required for a Quebec personal loan; this doesn’t need to be employment income, but it must be regular. Credit Score A high credit score is an indication of financial reliability; those with good credit get lower personal loan interest rates. Financial Commitments Your pre-existing financial commitments may affect your ability to make loan repayments; those with few other debts are considered safer. Assets Secured personal loans usually get the best interest rates in Quebec.
To find the best personal loan rates in Quebec, you need to start by ensuring you’re looking for the right product. Every type of Quebec personal loan is different, and as we’ve touched on above, choosing the right type of loan is essential to ensuring your loan funds help your financial situation rather than hurt it.
Once you have a specific type of personal loan in Quebec in mind, the next thing to do is to compare private loan lenders in Quebec. We’ve named the main type of lenders above; check them all out, comparing overall loan cost, not just interest rates. Don’t forget about online personal loan lenders; as online loans in Quebec have fewer overheads, they can offer cheaper rates than loans from brick-and-mortar lenders. Lastly, don’t forget to take into account any factors that may help lower your rates - for example, by offering security for the loan.
There are many private lenders for personal loans in Quebec, and choosing the right one for you when so many offer competitive personal loans may seem difficult. But there are ways you can distinguish the best lenders.
We mentioned above the importance of selecting the right type of personal loan for your situation, and then finding private loan lenders in Quebec that offer this type of loan to borrowers like you. This requires looking at factors such as: Types of personal loan offered Borrowing limits (as some lenders only offer small loans in Quebec) Repayment structures Eligibility criteria and required documentation Loan fees Interest rates Application process Application processing times
Beyond finding private personal loan lenders in Quebec that may be able to provide you with a loan to suit your needs, there is also the matter of reputation. It is important - for any financial decision - to work with a trusted company with transparent policies. So ask yourself: how long has the lender you are considering been in business? Do they have a proven track record? What are their past customer reviews like, and what types of customer service do they offer? Are their terms and conditions transparent, or is there a lot of small print? Don’t just look at their policies and availability during the sales process - you need to make sure that you’ll be able to access their assistance at any point in your loan journey. That’s why we at Smarter Loans only work with proven, reputable lenders in Quebec.
Qualifying for a personal loan in Quebec isn’t as tough as you may think. There are only a few hard and fast rules: You must be at least 18 years old You must have an active bank account You must be able to prove residence
Beyond these necessities, the criteria for qualifying for a Quebec personal loan can depend on the lender you go to. Private lenders for personal loans in Quebec use differing rules regarding eligibility, with some focusing on credit, others on income, and others on a combination of financial factors. You can use this to your advantage, to seek out and apply to lenders whose qualification rules you pass.