One application. 13 lenders.
Apply Now One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.
Thirteen lenders in the Smarter Loans network serve the province, from $15 advances to $35,000 instalment loans, at rates from 0% on the smallest fee-priced advances up to the 35% federal cap. Eight of the thirteen pay out within 24 hours, and nine consider poor credit or set no minimum score at all; four want a fair score. Income minimums run from $1,000 to $2,500 a month depending on the lender, from any regular source.
That is four fewer than the seventeen on the national personal loans page, because four lenders in the network do not lend in Alberta. The thirteen that do serve Calgary and Edmonton the same way; the Calgary page lists the same lenders for the city, and the bad credit loans in Alberta page narrows the set to the nine that consider a poor score.
On our platform in the first half of 2026, Albertans made 19.5% of personal loan applications across Canada, second only to Ontario, and asked for $5,790 on average. At the everyday scale, under $1,500, Albertans made 18.9% of applications and asked for $499.
Use those figures to check your own request. A personal loan around $6,000 is the ordinary case in the province; a request far above your income pushes you to the top of a lender's range or to a decline, and one well below the average is an everyday advance, which is a different product priced by fee rather than APR.
Alberta's high-cost credit regulation treats any credit at 32% APR or more as high-cost credit, and every lender offering it in the province, online included, must hold an Alberta high-cost credit licence. The federal cap is 35%, so a loan priced between 32% and 35% is legal but licensed, and a licensed lender must give you the total cost of borrowing in dollars, the annual rate and every fee before you sign.
Several of the lenders listed price up to 35% for a poor score, which means they operate inside Alberta's regime. That is not a mark against them; it is a protection for you, and it is worth asking any lender quoting above 32% for its Alberta licence number.
Rates run from 0% to 35%. The 0% is real but narrow: fee-priced advances of a few hundred dollars for a subscription rather than interest. Personal loans from $1,500 up carry an APR, and where you land is decided by your credit band first and your income regularity second. On our platform nationally, 46.3% of personal applicants are in the fair band and 23.6% below 560; the lenders listed are built for that, and a poor score gets the top of a lender's range or a lender that decides on bank statements instead. Twelve of the seventeen personal lenders in the network consider a score under 560, and nine of the thirteen that serve Alberta do.
A regular income of at least $1,000 to $2,500 a month depending on the lender, from any source that arrives on a fixed date, benefit income included with most lenders. A bank account it is paid into and your online banking login, because the decision is made on your statements. Three months of statements showing regular deposits and no returned payments, which matters more than the score with the lenders that decide on banking. An Alberta address.
Under $1,500 and repayable on your next pay date: a payday loan, capped in Alberta at $14 per $100 and 62 days. Under $1,500 but needing a few months: a short-term loan under the 35% cap, which the cash loans in Alberta page covers. $1,500 to $35,000: a personal instalment loan from the lenders listed. Larger, against a home: a home equity loan in Alberta. Enter the amount you need and the application routes on it.
Reviewed by Rafael Rositsan, Co-Founder and CEO, Smarter Loans. Last reviewed 18 September 2026. Lender figures are the lenders' published terms as checked August 2026. Platform figures cover applications from 1 January to 30 June 2026.
When Should You Use a Personal Loan in Canada?
When a personal loan is the right tool and when it is not: what Canadians borrow for, what it costs against a credit card,…
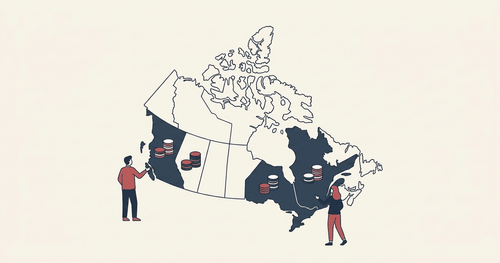
What Canadians Borrow to Consolidate, by Province
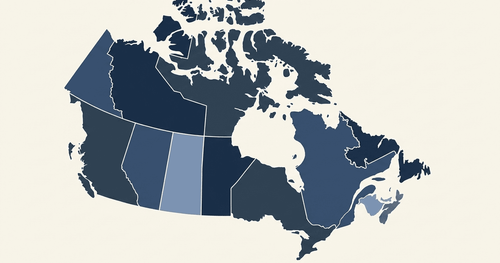
Canadians applying to consolidate debt asked for an average of $6,659 in the year to July 2026, across more than 8,000 Smarter Loans applications. Newfoundland and Labrador led every province at $7,948 and New Brunswick sat lowest at $6,133.
Credit Bands Across Canada: Who Applies With What Credit
Fair credit is the largest self-reported band in almost every province, across more than 40,000 Smarter Loans personal loan applications in the year to July 2026. Saskatchewan is the only exception, where low credit leads, and good or great stays under one in seven everywhere.
How to Judge a Loan Company in Canada
What separates a reliable loan company from a risky one in Canada: licensing, real APRs, fees in writing, and what borrowers like you get…
Thirteen lenders in the Smarter Loans network serve Alberta, from $15 to $35,000 at 0% to 35%. Eight pay out within 24 hours and nine consider poor credit or set no minimum score. One application reaches all thirteen.
On our platform in the first half of 2026, Albertans asked for $5,790 on average for a personal loan and $499 for an everyday advance under $1,500. Alberta made 19.5% of personal loan applications across Canada.
Alberta treats any credit at 32% APR or more as high-cost credit, and every lender offering it in the province must hold a provincial licence and disclose the total cost of borrowing before you sign. The federal cap is 35%, so a loan between 32% and 35% is legal but licensed.
Yes. Nine of the thirteen lenders listed consider poor credit or set no minimum score, and the decision is often made on three months of bank statements rather than the score. Expect a rate toward the top of a lender's range.
At least $1,000 to $2,500 a month depending on the lender, from any regular source, including benefit income with most lenders. Regularity matters more than the amount: a deposit that arrives on the same day each month is what lenders that decide on banking are looking for.