One application. 7 lenders.
Apply Now One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.

Your Canadian credit file does not transfer, which is the single biggest difference and the reason down payments are larger.
| Down payment | Commonly 20% to 30%, higher than a domestic purchase, because the lender is underwriting a foreign borrower. |
| Credit history | Canadian credit reports generally do not transfer. Some cross border lenders will consider them; others require a US file first. |
| Lender options | Cross border lenders, and some Canadian banks with US operations. Local US lenders rarely accommodate non-residents. |
| Currency | The mortgage is in US dollars. Exchange movement affects your effective payment every month. |
Yes, and the obstacle is not being Canadian. It is that a Canadian credit history does not produce a US credit score, and most American lenders underwrite to one. Two routes get around it, and they suit different buyers.
A Canadian bank's cross-border program. Several Canadian banks lend on US property to their existing clients, using your Canadian credit and income, with the mortgage arranged in Canada and registered in the US. Simpler paperwork, familiar underwriting, and usually limited to certain states and to a client relationship that already exists. If you bank with an institution that offers one, it is the first call.
A US lender's foreign-national program. American lenders that specialise in non-resident buyers underwrite on Canadian documentation: income, assets, a Canadian credit report they read manually. More flexible on property and location, more work to arrange, a larger down payment and a higher rate.
One mortgage lender in the Smarter Loans network, 8Twelve Mortgage, arranges US property financing for Canadians through its lending partners, and our application reaches it. The other six lenders listed are Canadian mortgage lenders shown because they render on every mortgage page in the network; they do not lend on US property.
More than the border. The product itself is built differently, and four differences decide most of the cost.
The term. A thirty-year fixed rate is the standard American mortgage, and it does not exist in Canada. Your rate holds for the life of the loan; there is no renewal every five years and no interest rate differential if you break it. Penalties for prepayment are rare.
The down payment. A foreign national puts down more than a domestic buyer: 25% to 35% is the usual range, sometimes more on a second home or an investment property.
Closing costs. Higher than in Canada and structured differently: title insurance, escrow, lender fees, and in some states a transfer tax. Budget 2% to 5% of the price.
Property taxes and insurance. Both vary enormously by state and county, and in coastal and hurricane-exposed markets insurance has risen sharply. A Florida property's carrying cost can be double what the mortgage payment suggests. Get both numbers for the specific property before you make an offer.
It moves it every month, for the life of the loan. Your payment is in US dollars; your income is in Canadian dollars; the exchange rate sets the difference.
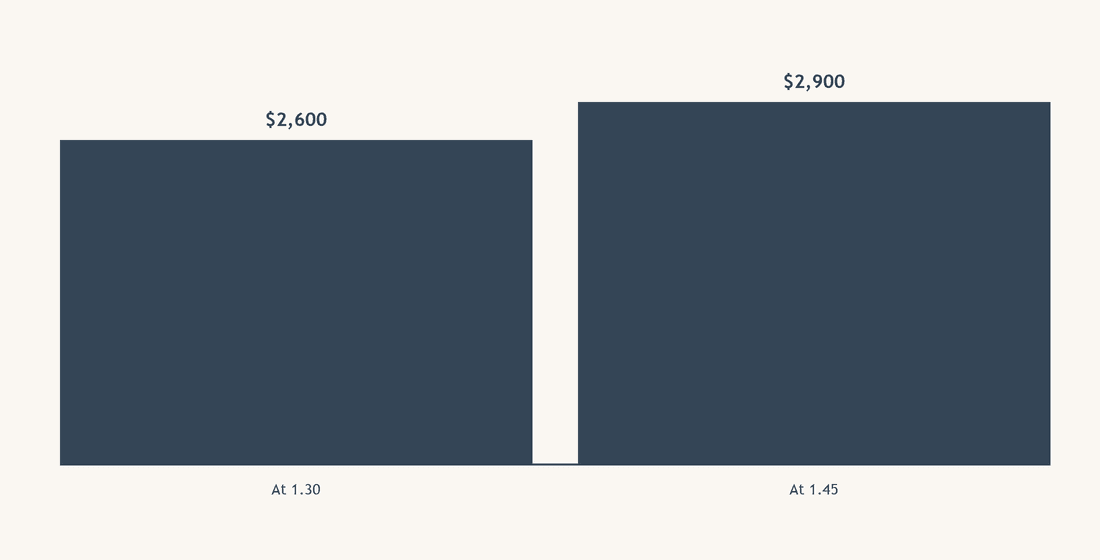
| A US$2,000 monthly payment | Canadian cost |
|---|---|
| At 1.30 | C$2,600 |
| At 1.45 | C$2,900 |
Use the table to stress-test the payment before you sign. A move in the exchange rate from 1.30 to 1.45, which the Canadian dollar has done inside a few years more than once, adds $3,600 a year to the same mortgage without a single term changing. A buyer who can carry the payment at today's rate but not at a weaker one is buying a currency position, not a house.
Two ways to manage it: earn or hold US dollars, from rental income on the property or US-dollar savings; or size the mortgage so that the payment at a weak Canadian dollar still fits. Rental income in US dollars is the natural hedge, and it is why many Canadian buyers of US property rent it for part of the year.
A down payment of 25% to 35%, in cleared funds, with a paper trail; US lenders check the source.
Canadian income and assets, documented. Notices of assessment, pay slips or business financials, bank and investment statements. A foreign-national lender reads these the way a Canadian B lender reads bank statements.
A Canadian credit report. Not a US score. The lender reads it manually and prices on it.
A US bank account, for the payments, and usually a US tax identification number, which the lender or a cross-border accountant will help you obtain.
The property, with a US appraisal ordered by the lender, and proof of insurance before closing.
Expect four to eight weeks from application to closing, longer than a Canadian mortgage, with the documentation and the US closing process accounting for the difference.
Four, and every one is worth cross-border advice before purchase rather than after.
Rental income is reportable in both countries. The Canada-US tax treaty prevents double taxation; it does not remove the filing obligation on either side.
US estate tax can apply to US real property held by a Canadian above a threshold that changes with US legislation. A Canadian estate can owe US tax on a Florida condo. Structures exist to manage it, and they are set up at purchase, not at death.
Withholding on sale. When a foreign person sells US real property, the IRS requires the buyer to withhold a share of the price against the seller's US tax. The withholding is recoverable against actual tax owed, but it is cash held back at closing.
Substantial presence. Spend enough days in the US across three years and you can become a US tax resident under the substantial presence test, with worldwide income reporting to match. Snowbirds track the days for this reason.
Many Canadians do, and for a second home used a few months a year the arithmetic sometimes favours it: no US mortgage costs, no currency risk on a payment, no foreign-national premium on the rate. The trade is the opportunity cost of the capital and, for many buyers, a Canadian home equity loan or refinance used to fund the purchase, which converts a US mortgage into a Canadian one at Canadian rates. The home equity loans and mortgage refinancing pages cover that route, and its risk: the security is your Canadian home.
Every tier of Canadian mortgage lending is on the mortgage lenders page.
Reviewed by Rafael Rositsan, Co-Founder and CEO, Smarter Loans. Last reviewed 16 September 2026. The currency example is illustrative.
Yes, two ways: a Canadian bank's cross-border program, which uses your Canadian credit and income for existing clients, or a US lender's foreign-national program, which wants a 25% to 35% down payment and Canadian documentation but no US credit score. One lender in the Smarter Loans network, 8Twelve Mortgage, arranges US property financing for Canadians.
Not for a cross-border program, and not for most foreign-national lenders, which read a Canadian credit report manually. What you need is documented Canadian income and assets, a down payment with a paper trail, and a US bank account for the payments.
More than a domestic US buyer: 25% to 35% is the usual range for a foreign national, and more on an investment property. Closing costs add 2% to 5% of the price on top.
It moves the payment every month for the life of the loan. A US$2,000 payment costs C$2,600 at 1.30 and C$2,900 at 1.45, a $3,600 difference over a year with no change to the mortgage. Size the payment to fit at a weak Canadian dollar, or earn US-dollar rental income against it.
It is reportable in both. The Canada-US tax treaty prevents double taxation but not the filing obligation. US estate tax, withholding on sale and the substantial presence day count are the other three rules that catch Canadian buyers, and all four are worth cross-border advice before purchase.