HomePersonal Loans › Bad Credit Loans in Alberta

Bad Credit Loans in Alberta

One application. 9 lenders.

Nine lenders in the Smarter Loans network lend to Albertans with a score under 560, through one application, from $15 advances to $35,000 loans at rates from 0% on the smallest advances up to the 35% federal cap. Six of the nine pay out within 24 hours, three set no minimum score at all, and income minimums run from $1,000 to $2,000 a month from any regular source. The decision is made on your bank deposits more than your score. Any lender charging 32% or more in Alberta must hold a provincial high-cost credit licence and disclose the total cost of borrowing before you sign. Rates checked August 2026.

Apply Now One application routed to where you qualify.

Your lender options

Every Apply button starts the same single application. Your chosen lender is prioritized first.
Show only lenders I qualify for
Four questions about you, and it filters this list instantly.
Amount: AnyCredit: Any Province: Any Sort: Recommended
★★★★★ 5.0 (2)
Amount
$30 - $250
Rate (APR)
0% APR
Terms
Revolving
Funding
2 days
Best for People who need a very small advance and want to avoid interest entirely · Line of credit
★★★★★ 4.5 (13)
Amount
$15 - $750
Rate (APR)
0% APR
Terms
0 - 3 months
Funding
1 hour
Best for People who need to bridge a small gap before payday without paying interest · Line of credit
★★★★★ 4.4 (14)
Amount
$500 - $35,000
Rate
From 9.99% APR
Terms
6 - 84 months
Funding
2 days
Best for Borrowers with fair or poor credit who want a long repayment runway and a path to better credit · Instalment loan
★★★★★ 4.6 (20)
Amount
$500 - $20,000
Rate (APR)
9.99 - 34.99% APR
Terms
9 - 84 months
Funding
2 days
Best for Borrowers who want branch support and the option to scale from a small unsecured loan to a large secured one · Instalment loan · Also offers: secured loan
★★★★★ 4.4 (11)
Amount
$3,200 - $20,000
Rate (APR)
19.8 - 34.99% APR
Terms
36 months
Funding
3 hours
Best for Borrowers with fair credit who want a fixed three-year payoff on a mid-size balance · Line of credit
★★★★★ 4.5 (13)
Amount
$1,000 - $5,000
Rate (APR)
19.9 - 34.5% APR
Terms
12 - 36 months
Funding
1 day
Best for Borrowers with poor credit and modest income who need $5,000 or less · Instalment loan
★★★★★ 4.7 (12)
Amount
$500 - $750
Rate (APR)
23% APR
Terms
3 - 6 months
Funding
1 day
Best for Borrowers who need a few hundred dollars quickly and want a rate well under the cap · Instalment loan
★★★★★ 4.6 (7)
Amount
$500 - $1,000
Rate (APR)
29.99 - 35% APR
Terms
3 - 4 months
Funding
1 day
Best for Small, short borrowing with the least paperwork: instant bank verification carries nearly every file · Instalment loan
★★★★★ 4.6 (16)
Amount
$500 - $10,000
Rate (APR)
34.99% APR
Terms
Revolving
Funding
1 hour
Best for Borrowers who want a payday advance and a longer-term line from the same provider · Line of credit

What gets a below-560 file approved in Alberta

This field removes more declines than credit score does.

Banking history can replace credit history. Lenders that connect read-only to your account assess deposit regularity instead of your file. They approve applications a bureau score would decline, and they fund fastest.

Ask for what you need. Approval likelihood falls as the amount rises against income, and at this band there is no version where a below-560 file gets prime pricing.

People with damaged credit in Alberta ask for less, not more. The table above shows it at both scales, and it runs against the assumption most people bring to this page.

The provincial rule that matters at this band

Alberta requires a high-cost credit licence for lending at or above 32% APR, and nearly all lending at this credit band sits above that threshold. The register is public: check it before signing anything near the cap.

What actually moves a Canadian credit score

  1. Payment history first. It is the heaviest factor, and one missed payment costs more than any optimisation recovers
  2. Utilisation second, and fastest to respond. Below 30 percent of limits, movement shows within two cycles
  3. One application, not several. Each separate full application is a hard inquiry
  4. Instalment credit adds mix to a card-only file, which is where a reported small loan earns its fee
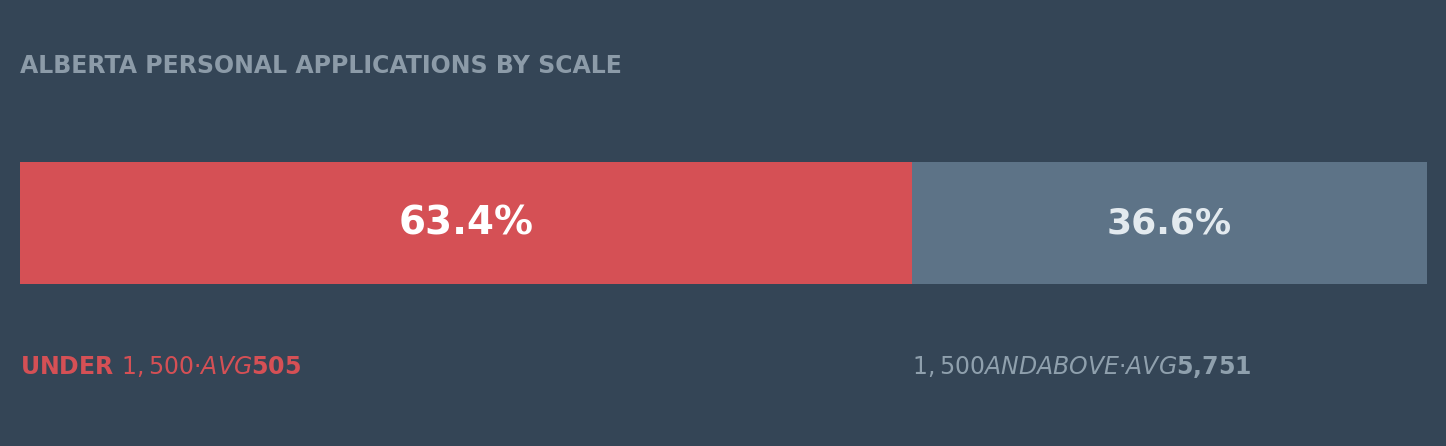
WHAT BELOW-560 APPLICANTS IN ALBERTA REQUEST
Below 560All credit bands
Everyday, under $1,500$493$505
Instalment, $1,500 and above$5,171$5,751
Smarter Loans platform data, twelve months to September 2026. Applications with a province recorded. Provincial and city figures do not sum to national totals.
WHAT A $500 LOAN COSTS FOR 14 DAYS IN ALBERTA
Payday loan ($14 per $100)
$70
Line of credit (30.4% APR)
$5.83
Instalment loan (5.99% APR)
$1.15
Interest for 14 days at each product's Alberta rate. A payday loan is repaid in one payment; credit products repay over a longer schedule and can cost more in total if carried for months.

Which lenders lend below 560 in Alberta?

Nine in the Smarter Loans network, and every one of the nine considers a score under 560: six because they consider poor credit as a matter of course, three because they set no minimum score at all. That is nine of the thirteen personal lenders that serve the province on the personal loans in Alberta page, and nine of the twelve in the network that lend below 560 nationally on the bad credit loans in Canada page. Amounts run from $15 advances to $35,000 instalment loans, rates from 0% on the smallest advances up to the 35% federal cap, six of the nine pay out within 24 hours, and income minimums run from $1,000 to $2,000 a month from any regular source.

What decides the approval if not the score?

Your bank deposits. The lenders listed read three months of statements through your online banking login before they read the score: regular income arriving on a predictable day, and an account without returned payments, is what they are looking for. The label you give your income decides which lenders see the application at all, so know whether you are full-time, self-employed, on disability or on benefits and say so. Some lenders use a soft inquiry that does not affect your score and decide on the statements alone.

What does bad credit cost in Alberta?

A rate toward the top of a lender's range, which for a poor score often means between 32% and 35%. Alberta's high-cost credit regulation treats any credit at 32% APR or more as high-cost credit, and every lender offering it in the province must hold an Alberta high-cost credit licence and give you the total cost of borrowing in dollars, the annual rate and every fee before you sign. That licence is a protection, not a warning, and it is worth asking any lender quoting above 32% for its number. On $5,000 over 36 months, the difference between 20% and 35% is roughly $1,450 in interest, which is why a loan repaid cleanly for a year and then refinanced at a rate that reflects the new score is the route out.

Before you apply

  • Have three months of statements ready. They matter more than the score.
  • Know your income label and enter it correctly.
  • Borrow the amount you need, since a poor score is priced on every dollar.
  • Ask for the Alberta licence number from any lender quoting 32% or more.
  • Apply once. Our application reaches all nine lenders and is sent where you are most likely to qualify; several applications in one week look like desperation to all of them.

Reviewed by Rafael Rositsan, Co-Founder and CEO, Smarter Loans. Last reviewed 22 September 2026. Lender figures are the lenders' published terms as checked August 2026; the cost example is illustrative.

Common questions

Can I get a loan in Alberta with a credit score under 560?

Yes. Nine lenders in the Smarter Loans network lend below 560 in Alberta, three of them with no minimum score at all, from $15 to $35,000. The decision is made on your bank deposits more than your score, and six of the nine pay out within 24 hours.

What rate will I pay with bad credit in Alberta?

Toward the top of a lender's range, often between 32% and 35% for a poor score. Above 32% the lender must hold an Alberta high-cost credit licence and disclose the total cost of borrowing before you sign.

What income do I need?

At least $1,000 to $2,000 a month depending on the lender, from any regular source that arrives on a fixed date. Regularity matters more than the amount.

Will applying hurt my credit?

Some lenders listed use a soft inquiry that does not affect your score and decide on your bank statements. Apply once through our application rather than to several lenders separately, because a burst of hard inquiries in one week counts against you.

How do I get a better rate next year?

Twelve clean months on a loan that reports to the bureaus, revolving balances brought down, and no new credit in the months before you refinance. A loan taken at 35% and repaid on time is refinanced at a rate that reflects the new score.

One application. 9 lenders. Apply Now
COMPARE Pick a lender Pick a second Compare these two →