One application. 11 lenders.
Apply Now One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.
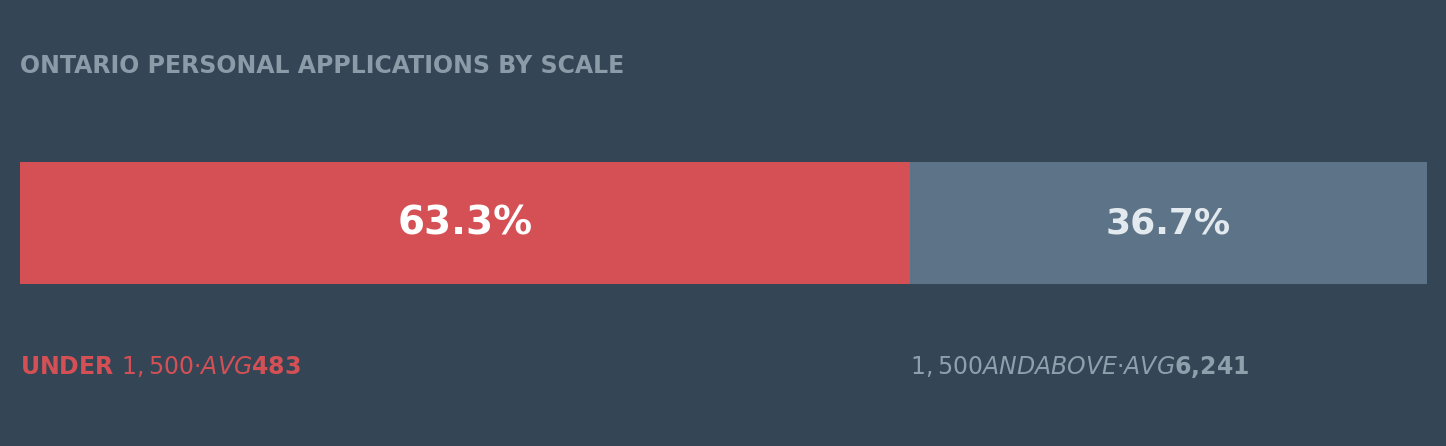
| Segment | Share | Average request |
|---|---|---|
| Everyday, under $1,500 | 63.3% | $483 |
| Instalment, $1,500 and above | 36.7% | $6,241 |
This field removes more declines than credit score does.
Banking history can replace credit history. Lenders that connect read-only to your account assess deposit regularity instead of your file. They approve applications a bureau score would decline, and they fund fastest.
Ask for what you need. Approval likelihood falls as the amount rises against income, and at this band there is no version where a below-560 file gets prime pricing.
People with damaged credit in Ontario ask for less, not more. The table above shows it at both scales, and it runs against the assumption most people bring to this page.
Ontario has no provincial high-cost credit band; the federal 35% cap is the protection. Anything above it is a criminal rate.
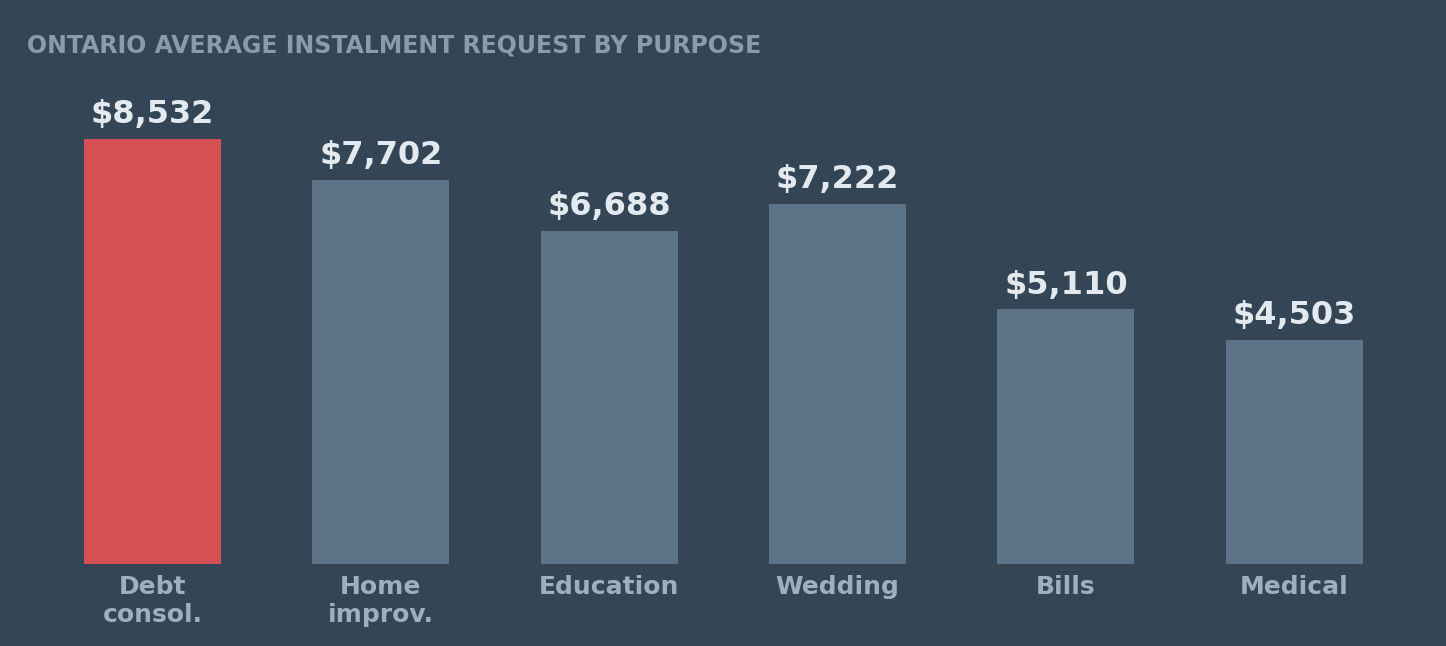
| Purpose | Average instalment request |
|---|---|
| Debt consolidation | $8,532 |
| Home improvement | $7,702 |
| Wedding | $7,222 |
| Education | $6,688 |
| Paying off bills | $5,110 |
| Medical expenses | $4,503 |
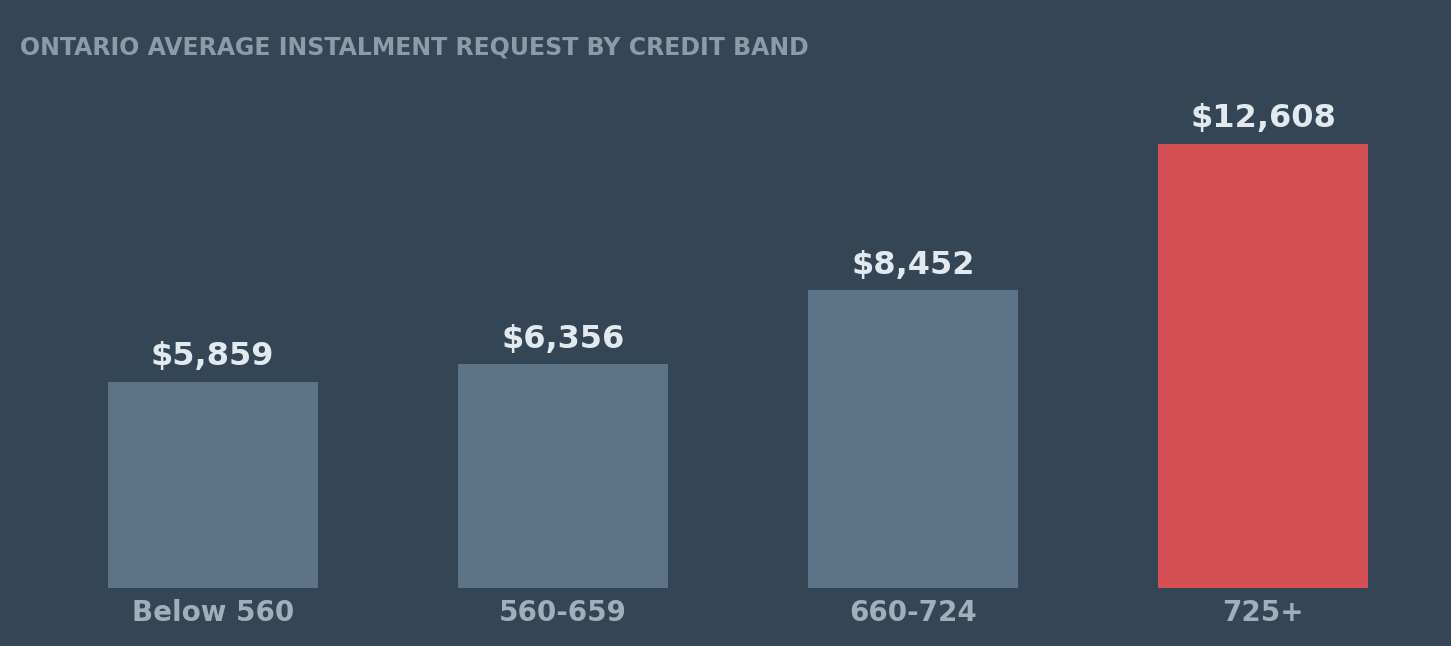
| Verified credit band | Average instalment request |
|---|---|
| Below 560 | $5,859 |
| 560 to 659 | $6,356 |
| 660 to 724 | $8,452 |
| 725 and above | $12,608 |
| Below 560 | All credit bands | |
|---|---|---|
| Everyday, under $1,500 | $487 | $483 |
| Instalment, $1,500 and above | $5,859 | $6,241 |
A low credit score can severely impact your access to financial products, so it's crucial for all Canadians to know their credit score and, if necessary, take steps to improve it. Luckily there are many ways to find out your current score, including: paying a fee to access the information via a credit bureau (such as Equifax or TransUnion), speaking to your bank or credit union, or using an online tool.
Credit scores are an important aspect of your financial profile; every consumer has one, and they range from 300 to 900 – the higher your score, the more financially secure you are considered to be. The average score across Canada is 650, although both Toronto and Ottawa have slightly higher averages than this (679 and 663 respectively). Anyone with a score over 650 is judged as having good credit (with those over 720 having very good or even excellent credit). Those with scores under 600 are considered to have bad credit, with scores lower than 500 rated as very bad.
If you live in Ontario and have a credit score of less than 600, you are probably eligible for a bad credit loan. You must also be at least 18 years old, be able to show ID and proof of residency, and have an active bank account. These are the basic qualification criteria; each lender may have their own eligibility requirements too, such as proof of income. Research your chosen lender's application criteria and make sure you have the documents they ask for. Then, complete the application form, including the supporting documents, and submit. If your application meets the lender's approval, then you're all done – you will receive a loan!
As Canada's most populous province, with nearly 40% of its citizens, Ontario has no shortage of bad credit providers. These fall into several major categories: online-only lenders, auto loan providers, bad credit specialists, and payday loan companies. Each has their own advantages and disadvantages, and to choose the right provider you must consider how much you need to borrow, for how long, and how much you can afford to pay for a loan.
Yes, it is possible to complete and submit an application for a bad credit loan entirely online. Ontario has online-only lenders, as well as general lenders with online platforms, and both have the ability to accept and process your information without you needing to go anywhere. Just make sure you have copies of all the required documents and submit everything as instructed.
Bad credit loans can be used for many different reasons: to help consolidate existing debts, to pay unexpected bills or cover emergencies, to ameliorate a short term cash flow issue, to fund a purchase, or to help improve your credit – really, you can use a bad credit loan for almost anything.
Interest rates for bad credit loans run a little higher than interest rates on traditional personal loans, but that doesn't mean you have no affordable options. The type and size of loan affects what rate you'll qualify for, as does your financial situation, so while the average interest rate for a bad credit loan in Ontario is around 20%, this can fall as low as 5%, or go as high as 40%, depending on the circumstances.
Bad credit loans are available in many sizes, from just a few hundred dollars to as much as $50,000. Your exact financial circumstances will dictate how much you can borrow, and under what terms. Generally speaking, the higher your income and the fewer other debts you have, the more you will be able to borrow.
Loans come with a variety of fees, and bad credit loans for Ontario residents are no different. Application fees and loan origination fees are pretty standard, but each lender may have other fees as well, including closing fees, late payment penalties, early prepayment fees, loan service fees, underwriting fees, and more. A reputable lender will always be transparent about their fee structure, and it's important to include all fees in your calculations regarding what you can afford.
Yes, no credit check loans are available in Ontario. This type of loan is exactly what it sounds like – a loan that does not require a credit check. This is useful if you have poor credit and would not pass a credit check, or if you do not want a credit check appearing on your report for some reason. Instead of credit score, your income level is the determining factor for approval. As no checks are required, these loans tend to be processed very quickly.
Taking on any form of debt, regardless of type, will always have an effect on your credit score – usually lowering it slightly. However, this effect does not need to be permanent. As with any loan, a bad credit loan will only have a long term negative impact on your credit score if you fail to pay back the loan as agreed. If you make all your loan payments though, you will actually help to improve your credit over time.

