One application. 9 lenders.
Apply Now One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.
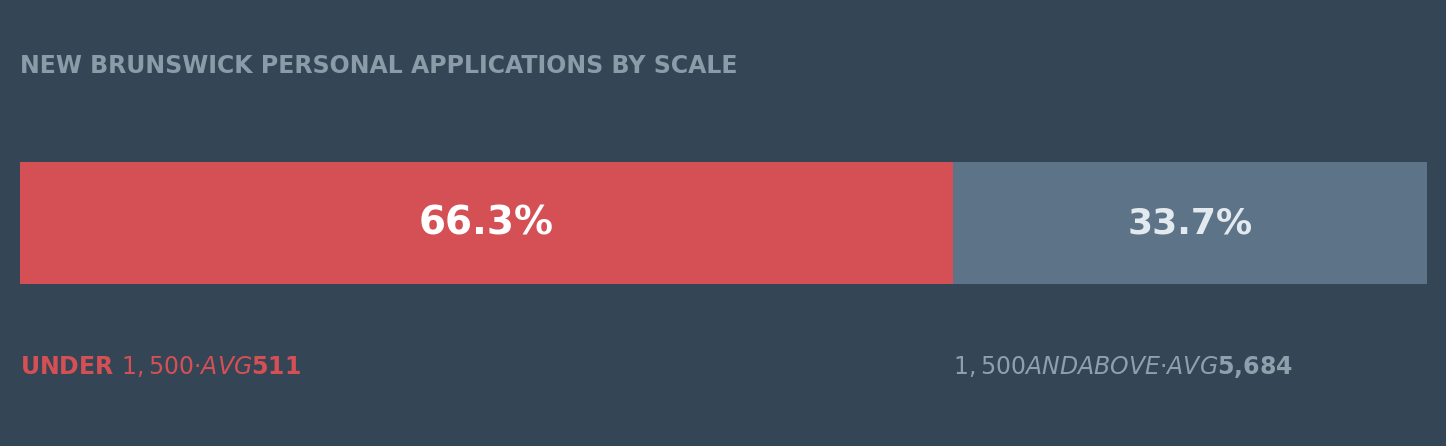
| Segment | Share | Average request |
|---|---|---|
| Everyday, under $1,500 | 66.3% | $511 |
| Instalment, $1,500 and above | 33.7% | $5,684 |
This field removes more declines than credit score does.
Banking history can replace credit history. Lenders that connect read-only to your account assess deposit regularity instead of your file. They approve applications a bureau score would decline, and they fund fastest.
Ask for what you need. Approval likelihood falls as the amount rises against income, and at this band there is no version where a below-560 file gets prime pricing.
In most of Canada, people with damaged credit ask for less than all-band borrowers. New Brunswick runs the other way at everyday scale: below-560 requests are slightly larger. The table above shows both.
New Brunswick relies on the federal 35% cap alone. Anything above it is a criminal rate.
| Below 560 | All credit bands | |
|---|---|---|
| Everyday, under $1,500 | $527 | $511 |
| Instalment, $1,500 and above | $5,570 | $5,684 |
Credit scores are a crucial part of your financial identity; every consumer has one, and they range from 300 to 900. The higher your score, the more financially secure you are. Anyone with a score over 650 is judged as having good credit, and those with scores under 600 have bad credit. Canada’s average score is 650, but New Brunswick falls slightly below that, with its residents averaging just 628.
Applying for a bad credit loan is fairly straightforward - especially if you do so online. The lender you choose dictates exactly what information you need to provide, but in general you’ll need to be at least 19 years old, a resident of New Brunswick, in possession of an active bank account, and be able to show you have some form of income. Depending on the type of loan you’re applying for, you may also need to show other financial documentation.
New Brunswick 775,000 residents have plenty of bad credit loan providers to choose from. These providers come in the form of online lenders, bad credit financial providers, no credit check lenders, bad credit auto loan providers, and payday loan companies. Choosing between these options means considering how much you need to borrow, for how long, and how much you can afford to pay for your loan. It’s also important to consider the reputability of the lender you get a loan from.
Interest rates on bad credit loans are much the same across the country, and range from 5% to over 40%. This range is due to the vast array of lenders that exist. For example, payday lenders charge much higher interest rates than other types of lender. The average APR for a bad credit loan sits at around 20%.
Generally, borrowing amounts for bad credit loans range from as little as $500 to as much as $50,000. The amount you can borrow will depend on the type of loan you get, the provider, and your exact financial circumstances (for example, a higher income will likely give you access to more borrowing room).
While most bad credit providers require some proof of income, it is still possible to get a loan if you have bad credit and no job. Unemployment loans are available from some lenders, but you will have to pay higher interest rates and will probably also have more restrictive loan terms, because of your increased financial insecurity. As these loans can quickly become very expensive, it’s worth considering if you can find a guarantor for your loan. This will make it much easier to qualify for a loan without income and with bad credit, and keep your rates down.

