One application. 13 lenders.
Get Funded One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.
Yes. It is easier than getting a personal loan with the same credit file, because a business has something a lender can underwrite that a person does not: revenue arriving in a bank account.
The numbers on our own platform show how little a score decides this. In the first half of 2026, half of all business loan applications on Smarter Loans, 49.6% of more than 400, carried no usable personal credit score at all. Another 24.4% sat in the fair band, between 560 and 659. Lenders serving this market are built for files that look like that, which is why they read your bank account instead of your credit report.
What poor credit changes is not whether you can borrow. It is which products reach you, how much they cost, and how much history the lender wants to see first.
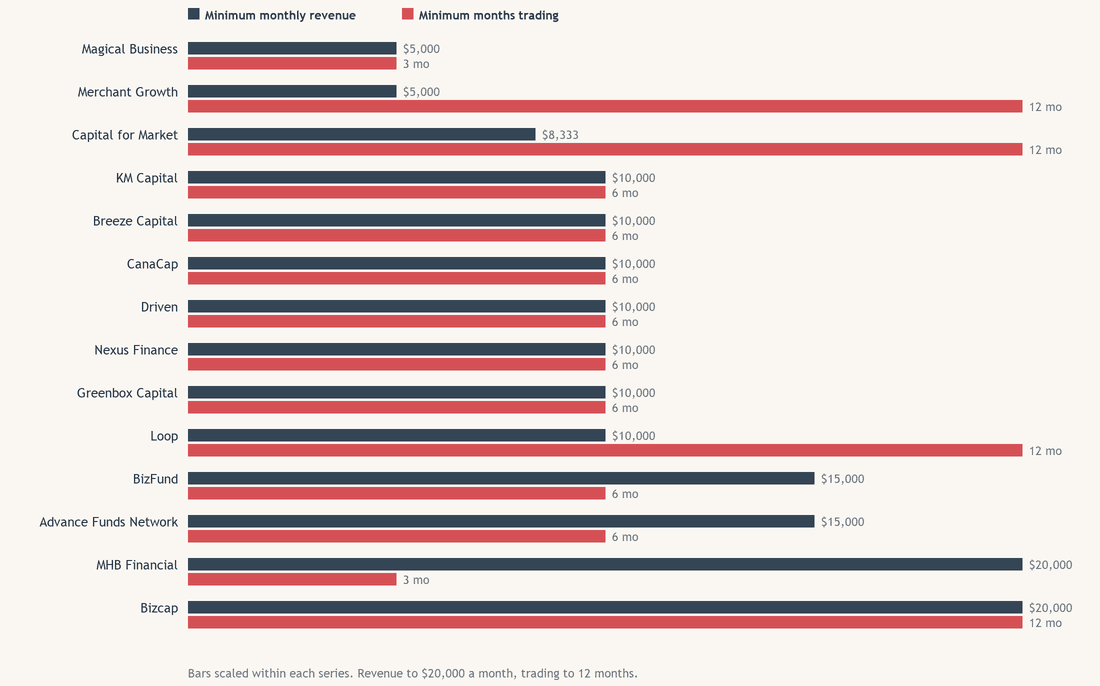
Every lender listed above publishes a minimum monthly sales figure and a minimum time in business. Those two numbers decide more applications than credit does.
| Lender | Minimum monthly revenue | Minimum months in business |
|---|---|---|
| Magical Business | $5,000 | 3 |
| MHB Financial | $20,000 | 3 |
| BizFund | $15,000 | 6 |
| KM Capital | $10,000 | 6 |
| Breeze Capital | $10,000 | 6 |
| CanaCap | $10,000 | 6 |
| Driven | $10,000 | 6 |
| Advance Funds Network | $15,000 | 6 |
| Nexus Finance | $10,000 | 6 |
| Greenbox Capital | $10,000 | 6 |
| Bizcap | $20,000 | 12 |
| Merchant Growth | $5,000 | 12 |
| Capital for Market | $8,333 | 12 |
| Loop | $10,000 | 12 |
Monthly revenue. The lowest sales minimum is $5,000 a month. The most common is $10,000. Four lenders want $15,000 to $20,000. If your deposits clear $10,000 a month with reasonable consistency, most of this page is open to you regardless of score.
Time in business. Two lenders will look at a business with three months in business. Most want six. Four want a full year. Across our whole business network, eleven of fifteen lenders fund businesses under twelve months old.
That matters because of who is applying. The average business applying through Smarter Loans has been trading 7.5 years, but 31.1% of applications come from businesses under two years old. A young business with poor owner credit is not an unusual file here. It is nearly a third of the pool.
Deposit consistency over deposit size. Lenders who lend against your sales connect to your business account and read it. Steady deposits every week beat a large lump every quarter. A slow month is not fatal; an erratic pattern is.
Owner credit, last. It sets the rate and the tier rather than the decision, and it counts for more at small amounts and at very young businesses. Nearly every product carries a personal guarantee, which is the only reason your score is checked at all.
Less than the headlines suggest, and less than the lenders' maximums.
| Request size | Share of business demand |
|---|---|
| Under $10,000 | 36.9% |
| $10,000 to $50,000 | 31.9% |
| $50,000 to $150,000 | 17.4% |
| $150,000 to $500,000 | 9.9% |
| $500,000 to $1.5 million | 3.6% |
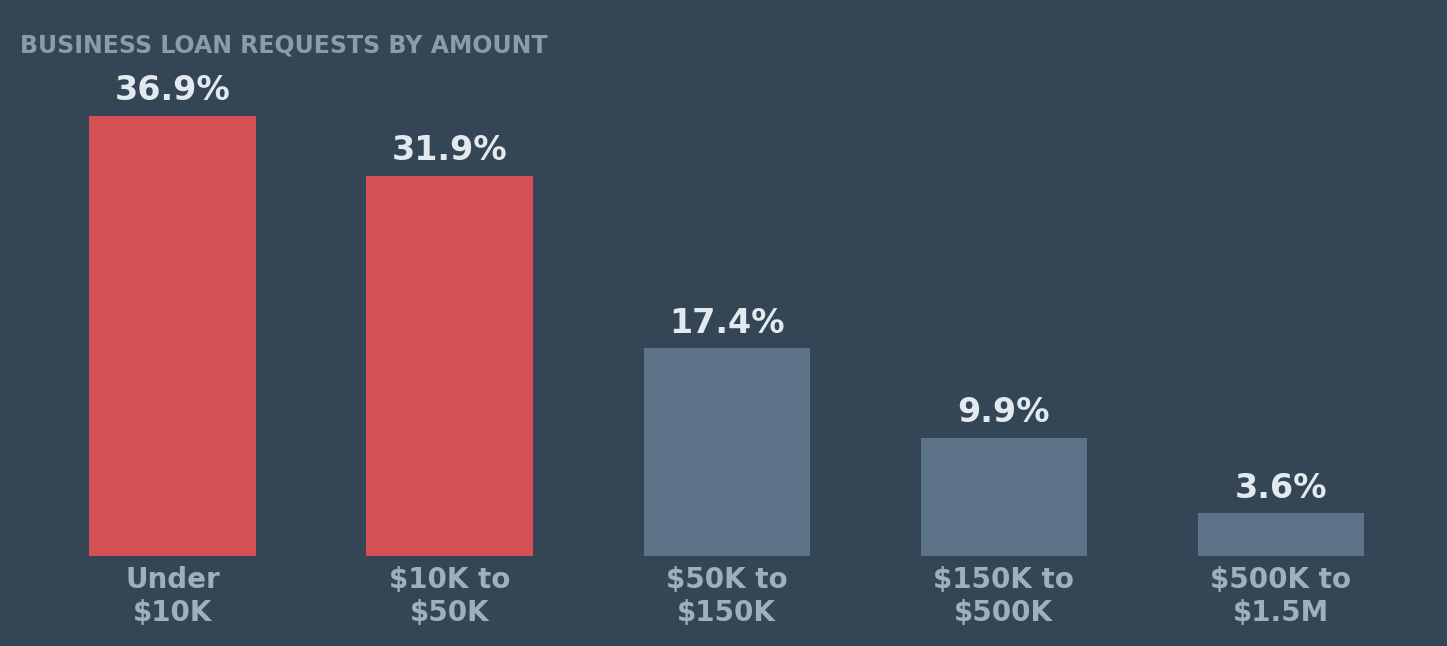
Across our platform, 68.8% of business requests are for under $50,000 and 36.9% are for under $10,000. Only 13.5% exceed $150,000. The overall average of $94,465 is pulled up by that top slice; the typical request is far smaller.
Two cuts from the same period are more useful for a bad-credit borrower than the average:
By purpose, everyday operations averages $89,090 and inventory $78,083, against $124,450 for starting a business. If you are borrowing to cover a gap rather than to expand, you are asking for something well inside what lenders who lend against your sales write. We do not see outcomes by credit band; the figures here describe what businesses ask for, not what they are offered.
Source for all figures in this section: Smarter Loans platform data, business loan applications, 1 January to 30 June 2026.
Both phrases are searched constantly. Neither describes a real product.
No credit check. No lender looks at nothing. What exists is a soft inquiry that does not touch your score, with the decision resting on bank data. Several lenders work exactly that way, and it is the honest version of what the phrase is looking for. A lender advertising no credit check at all is either describing a soft pull or describing something you should walk away from.
Guaranteed approval. No regulated lender in Canada guarantees approval before seeing an application. Where you see the phrase, read the rest of the page slowly. It usually sits beside fees that are due before any money arrives.
Rates run from 7% at the bottom of the term-loan range to factor rates of 1.1 to 1.5 on advances. Across our business network, twelve lenders price as APR and eleven as a factor, and several do both.
Merchant cash advance or revenue-share advance. The most widely available product at this credit band and the most expensive. Priced as a factor, repaid as a fixed share of daily or weekly sales, and the total does not fall if you repay early. Three of the thirteen lenders offer a factor-priced advance, and three lead with it. Our merchant cash advance page works through the true cost.
Short-cycle working capital. Three to twelve months, smaller amounts, priced from around 8%. Where the gap is genuinely short this is usually the cheaper route. See working capital loans.
Term loan outside prime criteria. Available from 7% to 10% at the lowest published rates, with the actual offer set by revenue and history. Terms run shorter than a prime borrower would get.
Line of credit, usually second. Revolving facilities want more history than a one-time advance, so this is often what you refinance into after a clean term rather than where you start. The business line of credit page explains how the limit gets set.
The rate a lender leads with is rarely the number that decides whether an offer is good. Run these two lines on any offer.
Factor-priced advance. Amount multiplied by factor equals total repayment. $40,000 at 1.3 repays $52,000. The cost is $12,000 whether you clear it in five months or twelve, and clearing it early saves nothing.
APR-priced loan. Payment multiplied by number of payments equals total repayment. $40,000 over eighteen months at 22% APR costs roughly $7,400 in interest, and clearing it early does cut that.
Same $40,000, and several thousand dollars between them depending on structure alone. The business loan calculator runs the APR version and the MCA true cost calculator converts a factor into a comparable figure.
Then one more check: model the repayment against your thinnest week, not your average one. Loans repaid from your sales fail when a slow month meets a fixed share of sales, and that is the failure the lender's own numbers will not show you.
Unsecured is the default at this credit band. Lenders who lend against your sales take a general security agreement and a personal guarantee rather than a specific asset. That is faster and it does not tie up equipment, but it is why the owner's credit is checked.
Secured against equipment or receivables lowers the rate and lengthens the term, and it opens lenders who would otherwise decline. If the money is buying something durable, finance it against that thing. Our guide to secured and unsecured business loans covers the trade in detail.
Startups face a different problem. With no trading history there is no bank account to read. On our platform, people starting a business through the business channel ask for $124,450 on average. People selecting the same purpose on a personal application ask for $9,657. Two very different populations, and if you are the second one, a personal loan may be the honest product for the first year.
Borrowing at this credit band is expensive enough that the alternatives are worth an afternoon before you apply.
The Canada Small Business Financing Program. A federal loan-guarantee programme delivered through banks and credit unions. Because the government shares the loss, a bank that would decline you outright may lend under it. Eligibility rests on the business, not the owner's score. Details at Innovation, Science and Economic Development Canada.
Supplier terms. Thirty extra days from a supplier costs nothing, does not appear as debt, and does not touch your credit. Ask before you borrow.
Provincial programmes. Every province runs small business financing or grant streams with their own criteria. Our guide to government business loans in Canada lists what exists where.
If credit is not actually your binding constraint, see all business financing options.
Reviewed by Vlad Sherbatov, Co-Founder and President, Smarter Loans. Last reviewed 2 September 2026. Platform figures cover business loan applications from 1 January to 30 June 2026.
Business Loans with Bad Credit in Canada
How Canadian lenders weigh revenue over credit, which products approve on cash flow, and what it costs when your personal file is the weak…
How Canadian Businesses Borrow: Purpose and Province
Canadian businesses asked for an average of $92,806 across 823 Smarter Loans business loan applications in the year to July 2026. Expansion carried the largest requests at $128,450 and Quebec the highest provincial average at $109,849.
Microloans for Canadian Entrepreneurs
Where Canadian microloans actually come from, who qualifies, what they cost, and when a small business loan beats one.
How to Qualify for a Business Loan in Canada
What Canadian lenders actually check: revenue, time in business and cash flow first, credit second. What businesses request, and which route fits.
Yes. In the first half of 2026, half of business applicants on our platform had no usable personal credit score and a further quarter were in the fair band. Lenders serving this market underwrite the business bank account, not the credit file. Expect loans repaid from your sales before term debt, and expect to pay more than a prime borrower.
No. Lenders who lend against your sales assess deposits, not profit. What they want is consistency across three to six months: steady weekly or monthly deposits rather than a few large ones.
Almost certainly. Nearly every product carries one regardless of incorporation. Your personal credit is assessed because of it, and if the business fails the debt follows you personally.
Two lenders accept three months in business; most want six; four want twelve. Across our network, eleven of fifteen business lenders fund under twelve months. Below three months, expect declines regardless of credit.
Not with no check at all. Several lenders use a soft inquiry that does not affect your score and decide on bank data instead. Any lender advertising no check whatsoever should be read carefully.

