One application. 7 lenders.
Get Funded One application routed to where you qualify.
Every Apply button starts the same single application. Your chosen lender is prioritized first.
The equipment is the security. That single fact explains almost everything else about how this kind of borrowing works, why it costs less than a working capital loan, and why lenders who would not touch your business on an unsecured basis will finance a $200,000 machine for it.
Because the lender can take the equipment back if you stop paying, it lends against the value of the asset rather than against your credit alone. That opens the door to businesses that are too young for a bank, and to owners whose personal credit is poor: every one of the seven lenders listed considers applicants with poor credit. It also means the term follows the working life of what you are buying. A truck or an excavator that will earn for ten years can be financed over ten years; a piece of technology that will be obsolete in three cannot.
The trade is that the lender's interest in the asset is registered, you cannot sell it until the loan is cleared, and a missed run of payments costs you the equipment your business runs on. Finance the things that earn their keep, over the period they earn it, and the structure works in your favour.
Almost anything with a resale market and a working life longer than the loan. In practice the seven lenders finance five broad categories.
Construction and heavy equipment. Excavators, loaders, cranes, compactors, generators. The deepest resale market of any category, which is why these carry the longest terms and the lowest rates. Our fleet financing page covers multi-unit purchases.
Transportation. Trucks, trailers, vans, forklifts. Commercial trucks have their own page, commercial truck financing, because the underwriting is specific to the trade.
Farming and agricultural equipment. Tractors, combines, irrigation, grain handling. Seasonal repayment schedules exist for this category; see farm equipment financing.
Medical and dental. Imaging, chairs, sterilisation, lasers. Regulated equipment with a licensing layer that lenders check; see medical equipment financing and medical aesthetics equipment.
Manufacturing and machinery. Presses, CNC machines, packaging lines, food processing. Long-lived, expensive, and usually financed over five to seven years.
Used equipment is routine across all five. The term is scaled to the remaining working life rather than the original one, and the rate is usually a point or two higher than on new, but the purchase price is lower, and for long-lived categories the used route is often the cheaper total cost.
A large share of the searches that reach this page are for leasing, and the honest answer is that the two products suit different equipment rather than different businesses.
Financing means you own the equipment at the end. Suits anything you will keep to the end of its life: heavy machinery, tools, most vehicles, anything with a long service life and a slow rate of change. The total cost is lower and the asset ends up on your balance sheet.
Leasing means the lessor owns it and you pay for the use. Suits equipment that goes out of date on a schedule: computers, some medical technology, anything you will want to replace in three or four years regardless of whether it still works. Payments are usually lower, obsolescence risk sits with the lessor, and there is often a buyout option at the end.
Most of the lenders listed offer both. The question to ask is not "which is cheaper" but "will this equipment still be earning in year six". If yes, finance it. If it will be replaced before then, lease it.
Rates start between 5.5% and 9.99% APR depending on the lender, and where you land inside a lender's range is decided by four things, in this order.
The asset. New equipment in a deep resale category gets the bottom of the range. Older equipment, specialised equipment, and anything the lender would struggle to resell moves the rate up and the term down.
The down payment. Ten to twenty percent is usual. More down means less at risk for the lender and a lower rate; it is the most effective lever you control.
Time in business and revenue. The two lenders at 5.5% both want at least twelve months in business and $10,000 a month in sales. Shorter history and thinner deposits move you to the lenders that accept six months, at higher rates.
Your credit. Last, because the equipment is the security. It sets the tier within a lender's range rather than the decision.
A worked example shows what the range costs. A $60,000 excavator over 60 months at 7.5% is about $1,202 a month and $12,137 in interest across the term. The same purchase at 9.99% is about $1,275 a month and $16,472 in interest. The gap between the two, roughly $4,300, is what a larger down payment or a newer unit buys. The equipment loan calculator runs any combination of price, down payment, term and rate.
Two things decide most applications, and neither is your credit score.
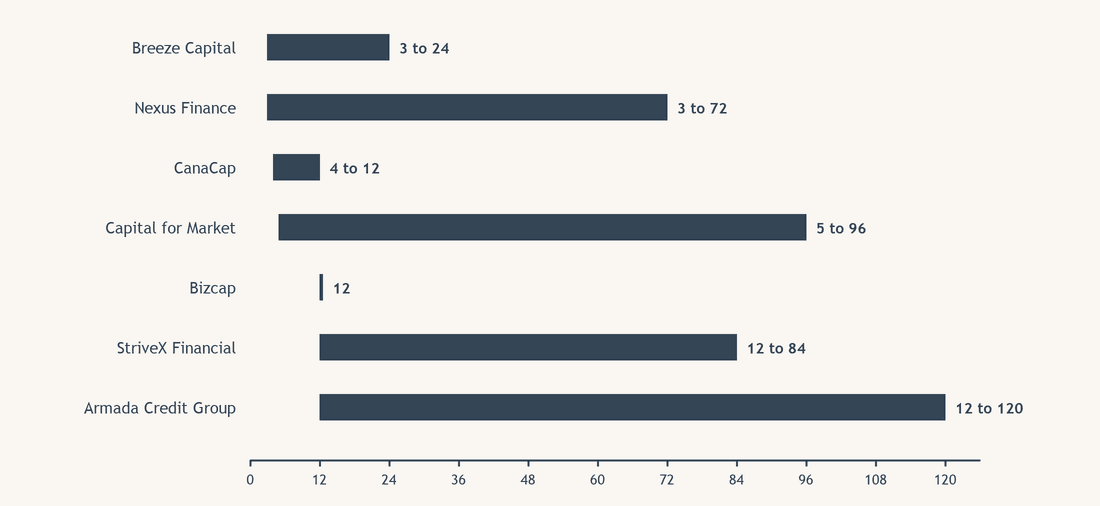
| Lender | Minimum monthly sales | Minimum months in business | Published term range |
|---|---|---|---|
| Breeze Capital | $10,000 | 6 | 3 to 24 months |
| CanaCap | $10,000 | 6 | 4 to 12 months |
| Nexus Finance | $10,000 | 6 | 3 to 72 months |
| Armada Credit Group | $10,000 | 12 | 12 to 120 months |
| Bizcap | $20,000 | 12 | 12 months |
| Capital for Market | $8,333 | 12 | 5 to 96 months |
| StriveX Financial | $10,000 | 24 | 12 to 84 months |
Time in business. Three lenders will look at a business after six months, three want a full year, and one wants two. The longer terms come from the lenders with the longer minimums; a six-month-old business gets a shorter loan from a lender that decides on bank deposits.
Monthly sales. Five of the seven want $10,000 a month; one accepts $8,333 and one wants $20,000. Lenders read your business bank account for this, and they are reading for regularity as much as size.
The quote. Equipment financing is priced against a specific purchase, so the application needs the dealer's or seller's quote, itemised. Lenders finance the invoice, not a round number.
Down payment. Ten to twenty percent of the price, more on older or specialised equipment. Some lenders finance one hundred percent for established businesses with strong statements.
Owner credit sets the tier, not the decision. On our platform in the first half of 2026, 49.6% of business applicants carried no usable personal credit score and 24.4% were in the fair band; the lenders listed are built for exactly that, because they are lending against the machine.
Yes to both, with more paperwork for the second.
Used equipment from a dealer is financed the same way as new, with the term scaled to remaining working life. A ten-year-old excavator with five years left gets a five-year term.
A private sale adds three steps every lender listed will require: a lien search on the equipment's serial number, so you are not buying something that already secures someone else's loan; an inspection or appraisal, because there is no dealer standing behind the condition; and payment direct to the seller by the lender, which protects both parties and confirms any existing lien is discharged. Budget two to three weeks for a private-sale purchase against days for a dealer purchase.
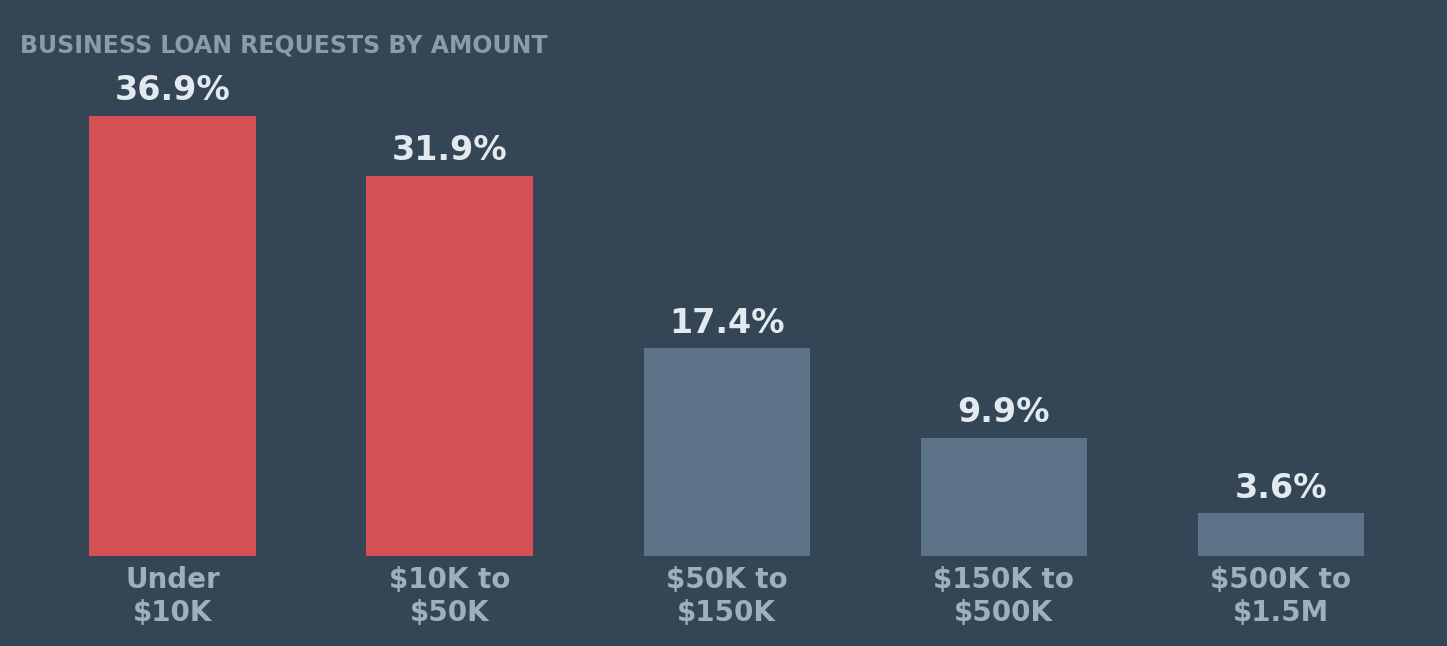
| Request size | Share of business demand |
|---|---|
| Under $10,000 | 36.9% |
| $10,000 to $50,000 | 31.9% |
| $50,000 to $150,000 | 17.4% |
| $150,000 to $500,000 | 9.9% |
| $500,000 to $1.5 million | 3.6% |
Use the figures below to size your request against a specific quote rather than a round number. Across all business applications on our platform in the first half of 2026, 68.8% were for under $50,000 and only 13.5% for more than $150,000; expansion requests, which is where most equipment purchases sit, averaged $118,580. The average business applying has been trading 7.5 years, but 31.1% of applications come from businesses under two years old, and that younger group asks for $82,937 on average against $108,510 for businesses trading five years or more.
Equipment purchases are not broken out as their own purpose in our data, so those figures cover all business borrowing. What they show is that most requests are far below the $50 million ceilings these lenders publish, and that a young business asking for a five-figure machine against its own quote is the ordinary case, not the exception.
Source for all platform figures: Smarter Loans business loan applications, January 2026 to June 2026, status Applied; request-size shares from the Smarter Loans Lending Demand Index, first half 2026.
The Canada Small Business Financing Program guarantees equipment loans through banks and credit unions and is worth checking first if you have two years of statements. Our guide to using equipment financing covers the accounting side, and all other business products are on the business loans page.
Reviewed by Vlad Sherbatov, Co-Founder and President, Smarter Loans. Last reviewed 14 September 2026. Platform figures cover business loan applications from 1 January to 30 June 2026.
Equipment Financing in Canada: How It Works
How Canadian businesses finance equipment, why the asset itself usually secures the loan, what lenders check, and when leasing beats buying.
How Canadian Businesses Borrow: Purpose and Province
Canadian businesses asked for an average of $92,806 across 823 Smarter Loans business loan applications in the year to July 2026. Expansion carried the largest requests at $128,450 and Quebec the highest provincial average at $109,849.
Secured vs Unsecured Business Loans in Canada
What business lenders take as security, what unsecured costs instead, and which fits at your revenue and stage.
How to Qualify for a Business Loan in Canada
What Canadian lenders actually check: revenue, time in business and cash flow first, credit second. What businesses request, and which route fits.
The lender finances a specific purchase and registers its interest in the equipment as security. You repay over a term matched to the equipment's working life, up to ten years on heavy machinery, and own it at the end. Because the equipment secures the loan, rates start lower than unsecured business borrowing, from 5.5% with these lenders, and lenders consider owners with poor credit.
There is no fixed score. Every lender listed considers applicants with poor credit, because the equipment is the security; what they check first is time in business, monthly sales and the quote. Credit sets where you land within a lender's rate range rather than whether you are approved.
Yes. The term is scaled to the equipment's remaining working life rather than its original one, and rates run a point or two above new. For long-lived categories like construction and farm machinery the used route is often the cheaper total cost because the purchase price is so much lower.
Finance anything you will keep to the end of its working life: machinery, tools, most vehicles. Lease anything that goes out of date on a schedule and that you will replace in three or four years regardless: technology, some medical equipment. Financing costs less in total; leasing puts obsolescence risk on the lessor.
Ten to twenty percent of the price is usual, more on older or specialised equipment. It is the most effective lever on your rate: a $60,000 machine at 7.5% instead of 9.99% over five years saves roughly $4,300 in interest, and a larger down payment is the most common reason a lender offers the lower rate.

